Why These 10 Melbourne Restaurants Get Location Right
Locatalyze Research Team
Location intelligence, Locatalyze
Melbourne publishes more of its own foot traffic than any other Australian city: 134 sensor locations counting hour by hour since 2009, every reading public. Sydney and Brisbane publish counts too — far fewer places, and in Sydney's case twice a year rather than continuously. We pulled a month of it and ran it against ten restaurants. The result is not the one the industry assumes: the retail street with the most people on it empties exactly when a dinner restaurant needs them, and one of the quietest streets we measured fills up. This is a location-intelligence read of ten Melbourne sites — not a food ranking, and not a claim about anyone’s private accounts.
How to read this article
**FACT** — supported by a named, linked source, or computed by us from a named open dataset with the method stated. **LOCATALYZE ANALYSIS** — our interpretation of that evidence. **INFERENCE** — a reasonable reading that is not proven. Pedestrian figures in this article are our own calculations from the City of Melbourne’s published sensor data for August 2026; the method is set out in full under [Method, evidence and limits](#method).
What this is not
This is not a claim that any restaurant named here is profitable, nor that its location caused its success. Trading figures, rent deals and margins are private and we do not estimate them. What is observable is the site: its catchment, access, anchors, competitors, published trading pattern, and — in the City of Melbourne — the measured pedestrian volume outside it. That is what we analyse. See our [methodology](/methodology) for how Locatalyze scores locations.
Key takeaways
Melbourne counts its own footpaths every hour, and publishes all of it
Every hospitality lease in Australia is signed on an assumption about how many people walk past and when. In most of the country that assumption stays an assumption. In the City of Melbourne it does not have to. The City of Melbourne runs a Pedestrian Counting System — sensors mounted under awnings and on poles that record multi-directional footpath movements, twenty-four hours a day, and have done since 2009. There are 134 sensor locations. Every hourly reading is published as open data.
We pulled the full month of August 2026 for eleven of those locations and calculated three things for each: the average pedestrian count on a weekday, the average on a weekend day, and the hour-by-hour profile. Then we compared the lunch window (11am to 3pm) with the evening window (6pm to midnight). The ratio between those two numbers is the single most useful thing in this article, and as far as we can tell nobody publishes it.
FACT: Bourke Street Mall’s north-side sensor recorded an average of 19,042 pedestrians a weekday in August 2026. Little Bourke Street in Chinatown recorded 6,960 — 37% as many. FACT: in the evening window, the Mall recorded 4,180 and Chinatown recorded 3,288 — 79% as many. LOCATALYZE ANALYSIS: measured per pedestrian, Little Bourke Street delivers more than twice as much dinner-hour trade as the busiest retail footpath in the city. The two are 335 metres apart.
One number in that table needs a warning label, because reading it naively is exactly the mistake this article is about. Melbourne Central shows an evening-to-lunch ratio of 1.24 and a 5pm peak — on the face of it, a dinner street. It is not. It is a station entrance, and its 5pm peak is people leaving the city, not arriving to eat in it. INFERENCE: an evening peak at a transport interchange measures departure, and an evening peak at a destination measures arrival. The counts cannot tell those apart. You have to know what the site is.
Where the data stops
The sensors are the City of Melbourne’s, so they cover the CBD, Carlton, Docklands, Southbank, North Melbourne and Kensington — and nothing else. There is no published count for Gertrude Street, Hopkins Street, Chapel Street, Glen Eira Road or Kingsway. For those sites we say so and reason from other evidence, rather than quietly extending a number that does not exist.
What the counts change about choosing a site
Read the shape before the size
A dinner restaurant does not need a busy street. It needs a street that is busy between six and nine at night, in a mood to sit down. Collins Street carries four times Errol Street’s weekday volume and produces less than half its evening-to-lunch ratio — 0.47 against 1.14. LOCATALYZE ANALYSIS: for an operator whose revenue is concentrated in dinner, the North Melbourne village strip is the better street on the evidence, and the CBD office spine is a lunch business wearing a prestige address.
The unit is the block, not the strip
The two Bourke Street Mall sensors sit 36 metres apart, on opposite footpaths of the same pedestrian mall. They differ by 36% — 19,042 against 13,973. On Lygon Street, two sensors 333 metres apart differ by a factor of two and a half. FACT: both distances are calculated from the coordinates the City of Melbourne publishes with each sensor. LOCATALYZE ANALYSIS: if a single mall varies by a third across its own width, a suburb-level number cannot possibly resolve a lease decision, and neither can a strip-level one. The unit that matters is the block, and often the side of it.
Trams make access mean something different here
Melbourne runs the largest tram network in the world: 24 routes, more than 250 kilometres of double track, about 1,600 stops and more than 147 million passenger trips a year (Transdev). LOCATALYZE ANALYSIS: that changes the parking conversation. On a tram-served strip, the relevant access question is how far your door is from a stop and how often the route runs at 10pm, not how many bays sit out the front. On a site the tram network does not reach — an industrial estate, a foreshore, a middle-ring centre — parking goes straight back to being decisive.
The lease is a claim on covers you have not sold
Measured footfall does not pay rent; converted covers do. The arithmetic that decides a site is how many covers per trading week it must produce, at your real average spend, before rent and wages clear — and then whether the street’s shape can deliver them in the hours you are open. FACT: four-year survival for Australian cafés, restaurants and takeaway food services was 51% for June 2021 to June 2025, against 63% for all businesses (Tourism Research Australia). Our guide to why a cheaper lease is often the more expensive location works through how that goes wrong.
Ten Melbourne sites, and what each one is really renting
These are not the ten best restaurants in Melbourne and they are not ranked. They were chosen to cover distinct location strategies, to be currently trading and publicly documented, and — where possible — to sit near a sensor so the reasoning can be checked rather than asserted. Three are in the city centre, which is deliberate: the CBD is the only part of Melbourne where the footfall claim can be tested against a public number.
1. Flower Drum — Market Lane, CBD — the street with the right shape
Flower Drum opened in 1975 on Little Bourke Street and moved about a decade later to 17 Market Lane, a few metres off it, for a larger dining room (Flower Drum). It has traded there ever since; Gilbert Lau sold it in 2003 to executive chef Anthony Lui and two colleagues. The dining room is upstairs. There is no shopfront doing any work at all.
On the numbers, this is the best-shaped restaurant location in our measured set. Little Bourke Street carries 6,960 pedestrians on an average weekday — a third of Bourke Street Mall, one street north — but its evening-to-lunch ratio is 1.93, the highest of the eleven locations we pulled, and its weekday peak is 6pm. On weekends the street lifts to 11,964, a 72% jump, while its evening shape holds. LOCATALYZE ANALYSIS: Chinatown is not a thoroughfare that happens to have restaurants on it. The restaurants are why the pedestrians are there, which is why the curve peaks when kitchens open rather than when offices empty.
The trade-off is that a destination street is only as strong as its collective reputation, and no single operator controls it. Chinatown’s evening volume is a shared asset built over decades; a decade of drift would take it away from every tenant at once. An upstairs room in a lane also has no capacity to convert a passer-by who has not already decided.
The lesson: buy the hour you trade in, not the hour the street is busiest. Locatalyze take: our model rates Melbourne CBD 64 out of 100 for restaurants — a CAUTION — which is a fair read of the average CBD tenancy. It is not a fair read of Chinatown, and the sensor data is why. See the Melbourne CBD location read.
2. Chin Chin — 125 Flinders Lane, CBD — the busiest footpath we measured
Chin Chin opened in mid-2011 at 125 Flinders Lane and trades from 11am until late (Chin Chin). Flinders Lane at Swanston Street is the busiest location in our measured set: 32,153 pedestrians on an average weekday, 35,464 on a weekend day, with an evening-to-lunch ratio of 0.91 and a 5pm peak. It is the rare CBD street that is genuinely busy all day and still busy at night.
That shape is what makes an all-day, high-volume format work here rather than a two-service one. LOCATALYZE ANALYSIS: a street with a flat, wide curve rewards a business that can take revenue in every hour it is open, and punishes one that can only sell between 6pm and 9pm. The site and the format agree with each other.
The venue is also a useful correction to a story the industry repeats. Chin Chin became famous for refusing reservations, and the queue became part of the brand. It now takes bookings. INFERENCE: the queue was a demand-capture decision, not a property one — and unlike the lease, it could be revisited. The lesson: the site is fixed for the term; the model you use to fill it is not. Check the lease-side questions in our pre-lease checklist for restaurants.
3. Pellegrini’s Espresso Bar — 66 Bourke Street, CBD — a cost base small enough to outlast everything
Pellegrini’s opened at 66 Bourke Street in 1954 and has traded on that site for more than seventy years. It sits at the Parliament end of Bourke Street, several blocks east of the retail core, in a narrow tenancy with a counter, a row of stools and a small back room. There is no sensor on that block; the nearest measured point, 231 Bourke Street, averages 10,625 pedestrians a weekday, and the count at number 66 will be lower again.
LOCATALYZE ANALYSIS: this is the clearest example in the set of a site chosen — and, more importantly, kept — at a scale its street can support. A counter and a back room need a fraction of the covers a large dining room three blocks west would need, and they have needed them through seven decades of retail cycles, recessions and a pandemic. Longevity of that kind is not a marketing achievement; it is an occupancy-cost achievement.
The trade-off is a hard ceiling. A site this small cannot be scaled, cannot absorb a rent shock by adding covers, and depends entirely on turning tables fast at a low average spend. The lesson: on a quiet block, size the room to the street rather than to the ambition. The most common Melbourne failure is the opposite — a large fit-out on a street that can only fill it two nights a week.
4. Cutler — 55–57 Gertrude Street, Fitzroy — one suburb, three different markets
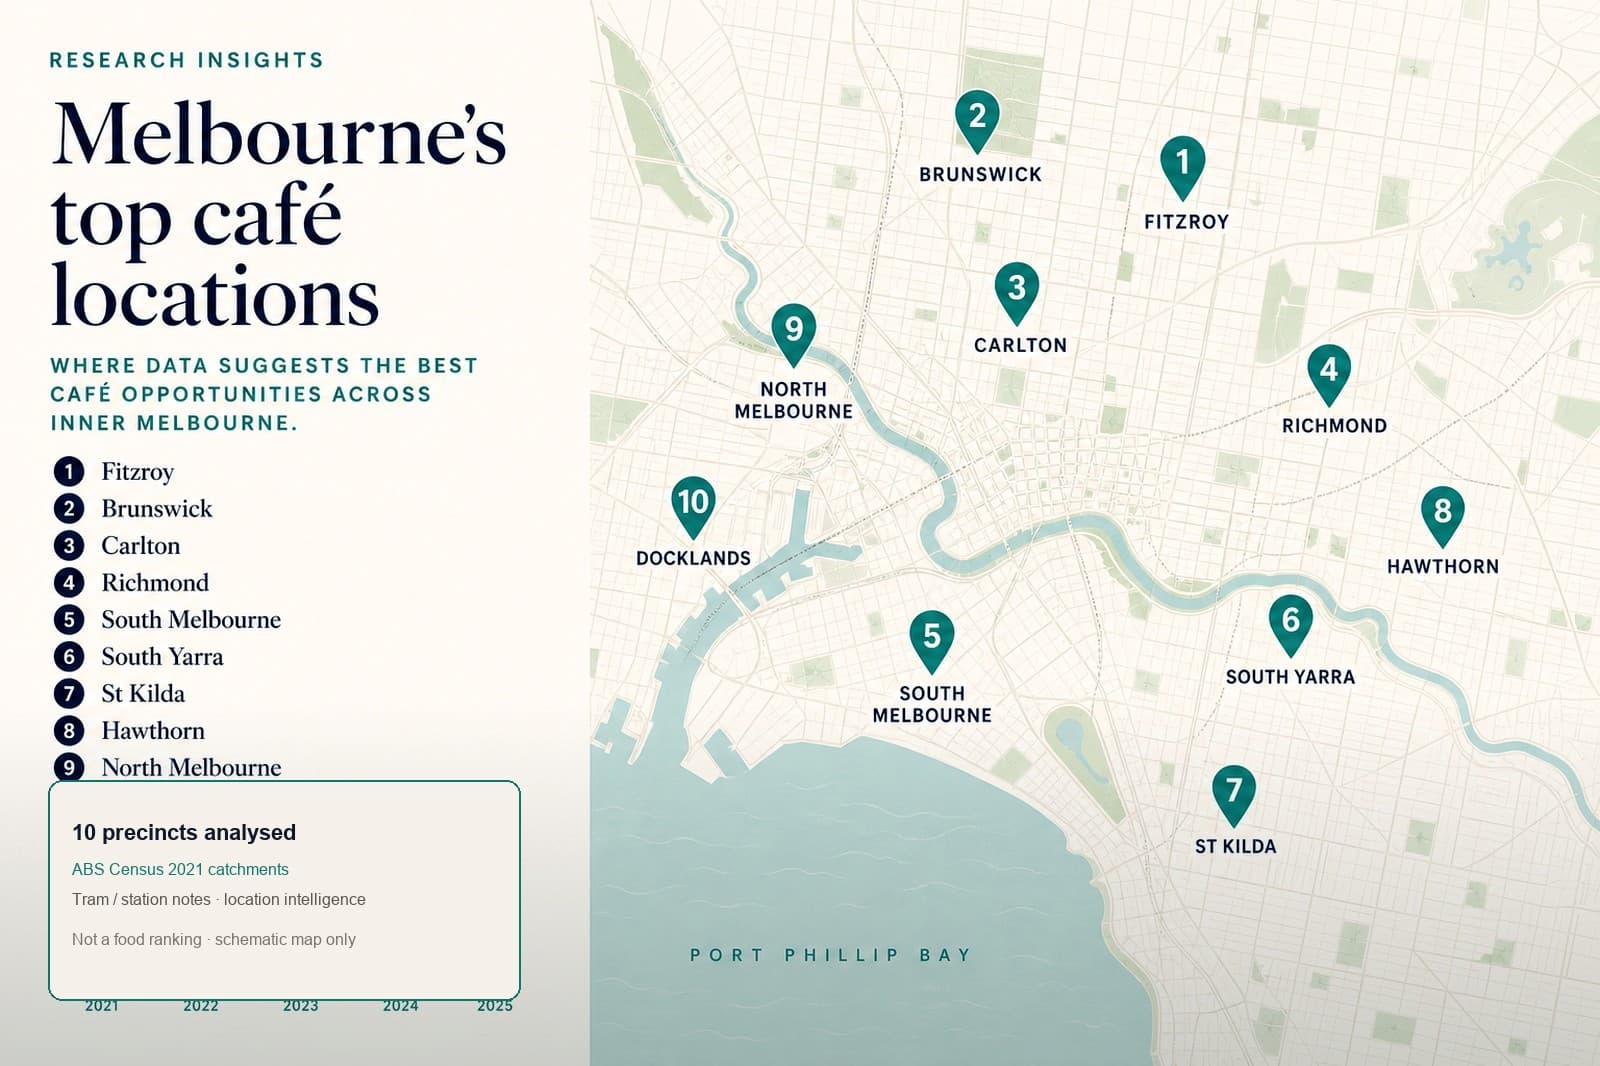
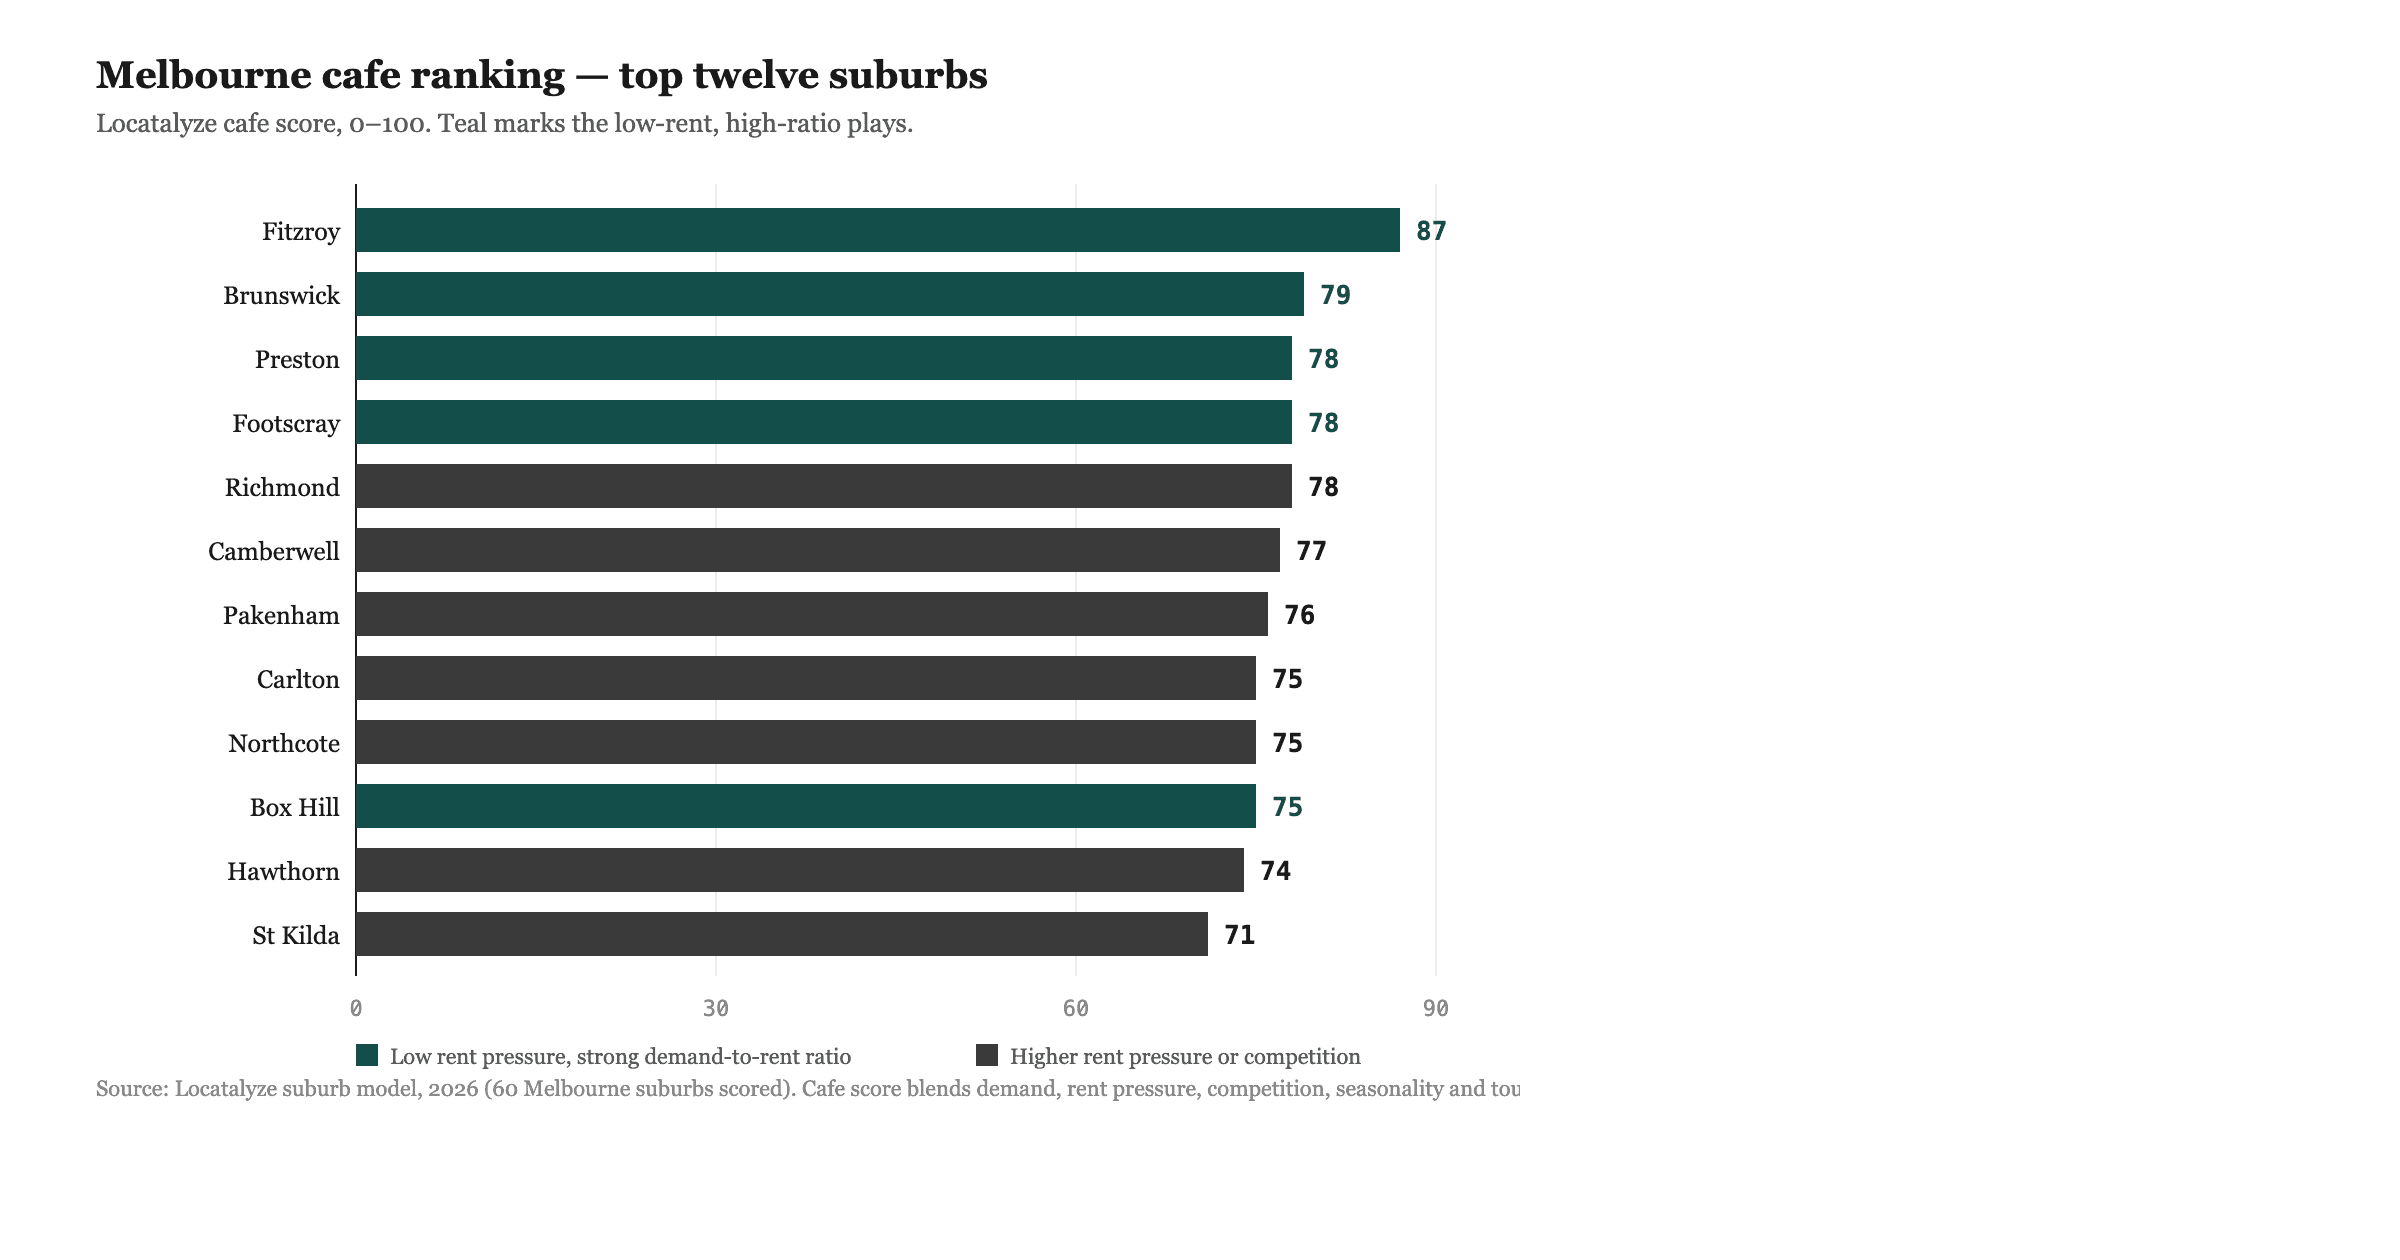
Andrew McConnell opened Cutler & Co, now trading as Cutler, in 2009 in a former metalworks at 55–57 Gertrude Street (Cutler). Fitzroy is the strongest suburb in our Melbourne model: 84 out of 100 for restaurants, a GO verdict, the highest of the 104 Melbourne suburbs we score. FACT: ABS 2021 recorded Fitzroy with 10,431 residents and a median weekly household income of $2,194, against $1,759 for Victoria (ABS QuickStats).
And that 84 is the least useful number in this article, because Fitzroy is not one market. It has three principal strips — Brunswick Street, Smith Street and Gertrude Street — and they behave differently. Gertrude is the short one, the one with the chef-driven rooms and the highest rents per metre of frontage. Brunswick Street is longer, more retail, more foot-driven and more volatile block by block. LOCATALYZE ANALYSIS: a single suburb score averages all three, which means it is wrong about each of them in a different direction. There is no sensor in Fitzroy, so nobody can settle this with counts — which is precisely why the strip-level judgement has to be made on the ground.
The trade-off Gertrude Street asks for is rent against reach. A short, expensive, well-known strip delivers a customer who already intends to spend, and charges for the privilege in occupancy cost and in competition from operators of the same calibre within two hundred metres. The lesson: never take a suburb score into a lease negotiation without first deciding which strip, and which end of it, you are actually buying. See the Fitzroy location read.
5. Tiamo — 303 Lygon Street, Carlton — the customers are not the residents
Tiamo has traded on Lygon Street since 1978 and has expanded next door and upstairs in the years since. Two facts about its street are worth putting together. FACT: the sensor at Lygon and Faraday, a short walk from Tiamo’s door, averaged 5,134 pedestrians a weekday in August 2026. FACT: the sensor 333 metres south averaged 2,034, and its evening-to-lunch ratio is 0.50 against the Faraday sensor’s 0.94. LOCATALYZE ANALYSIS: those are two different businesses on one street name, and the difference is a four-minute walk.
The second fact is the one that should stop an operator reading suburb demographics. FACT: ABS 2021 recorded Carlton with 16,055 residents, a median age of 27 and a median weekly household income of $1,292 (ABS QuickStats) — well below the Victorian median of $1,759. On resident income alone, Carlton looks like a weak restaurant market. It is not, because its demand engine is the University of Melbourne and RMIT next door, not household wealth. Our model rates Carlton 72 out of 100 for restaurants with a GO verdict, and the Carlton location read sets out why.
The trade-off is a student-shaped price ceiling and a student-shaped calendar. A catchment built on semesters empties in December and January, and it is unusually price-sensitive year-round. The lesson: identify who the catchment actually is before you read its income. A low median can mean poverty, or it can mean students — and those are opposite signals for a restaurant.
Weighing two Melbourne addresses on the same strip? Run each one through Locatalyze and compare demand, competition and rent pressure at the frontage rather than the suburb.
Free location score, map, data confidence and PROCEED / VERIFY / AVOID recommendation. Modelled financials stay optional.
Analyse a Melbourne address6. Moon Dog World — Chifley Drive, Preston — floor area a strip cannot sell you
Moon Dog World occupies a former factory at 32 Chifley Drive in a Preston industrial estate — a site of roughly 12,000 square metres, with 72 taps, a lagoon and a beer garden, and a capacity reported in trade coverage at around 725. It opened in October 2019 and trades weekday evenings from 4.30pm and from 11.30am on Fridays, Saturdays and Sundays (Moon Dog). There is no passing trade, no strip, no tram and no shopfront.
LOCATALYZE ANALYSIS: what industrial land buys is the one thing an inner-city strip cannot sell at any price — area, at a rate per square metre low enough that a room of that size and a car park are both affordable. The trading pattern follows the logic exactly. Weekday lunch does not exist on Chifley Drive, so the venue does not open for it. Weekends start late morning, because weekends are when people will make the trip.
The trade-offs are severe and worth stating plainly. Every customer is a deliberate visit, so the marketing budget replaces the frontage premium permanently rather than for a launch period. A venue that size has a fixed cost base sized for full weekends, and a wet Sunday in July is a real revenue event. Industrial zoning also constrains what the site can become later. The lesson: on cheap land, capacity is the product — and you have to be able to fill it without a footpath. Our model rates Preston 71 out of 100 for restaurants with a GO verdict, but that score describes Preston’s residential strips, not an industrial estate; see the Preston location read.
7. Pho Chu The — 92 Hopkins Street, Footscray — the interchange is the frontage
Pho Chu The trades at 92 Hopkins Street, directly opposite Footscray station and a short walk from Footscray Market, and has been operating for roughly three decades with a second site in Richmond. Hopkins Street and Leeds Street hold one of Melbourne’s densest Vietnamese dining clusters, established as Vietnamese operators took over the street’s shopfronts from the late 1980s.
FACT: ABS 2021 recorded Footscray with 17,131 residents, a median age of 34 and a median weekly household income of $1,763 (ABS QuickStats) — almost exactly the Victorian median. LOCATALYZE ANALYSIS: the resident base is unremarkable and it is not what carries the strip. Three engines sit on top of it: a station on the Werribee, Williamstown and Sunbury lines, a market that pulls a weekend shopping trip from across the west, and a cuisine cluster dense enough that customers choose the street before the venue. That combination is why a value-priced format can hold a main-street frontage here.
The trade-off is a price ceiling that the cluster sets and no single operator can lift, plus direct exposure to anything that changes station patronage. The lesson: where transport, a market and a cuisine cluster overlap, the frontage is doing three jobs at once — and that is worth more than a quieter address with a nicer fit-out. Our model rates Footscray 71 out of 100 for restaurants with a GO verdict; see the Footscray location read.
8. Attica — 74 Glen Eira Road, Ripponlea — a site that does no work at all
Attica occupies a converted suburban bank building at 74 Glen Eira Road, Ripponlea. It opened in 2003, Ben Shewry became head chef in 2005 and bought the restaurant in 2015, and it has appeared on the World’s 50 Best Restaurants list every year since 2010. It serves dinner Tuesday to Saturday, seating guests between 6pm and 8pm (Attica). Five nights. One seating window. No lunch.
FACT: ABS 2021 counted 1,532 residents in Ripponlea (ABS QuickStats) — the smallest suburb in this article by an order of magnitude. Ripponlea is too small to carry its own page in our suburb model; the adjacent Elsternwick centre scores 61 out of 100 for restaurants, a CAUTION.
LOCATALYZE ANALYSIS: read those two facts together and the conclusion is unusual but hard to avoid. Attica’s site is not generating its demand — a global reputation and a booking system are. What the site provides is the opposite of what a normal restaurant location provides: quiet, parking, and a street where no other operator is bidding for the same shopfront. INFERENCE: for a business selling five nights of pre-booked tasting menus, visibility is worth very little and occupancy cost is worth a great deal, and a suburban road answers both.
The trade-off is total dependence on the reputation. There is no passing trade, no local catchment of any scale and no second daypart to fall back on; if the bookings stop the site cannot rescue the business. The lesson: the stronger your demand generation, the cheaper and quieter your site should be — and almost nobody has demand strong enough to justify Attica’s answer. That is the point of naming it: it is the boundary case, not the template.
9. Stokehouse — 30 Jacka Boulevard, St Kilda — one site, three price points
Stokehouse opened on the St Kilda foreshore in 1989, was destroyed by fire in 2014 and reopened in December 2016 as a rebuilt, stacked precinct: the upstairs restaurant, Pontoon downstairs on a no-bookings counter model — reported at the reopening as seating more than 250 inside and 150 outside — and Paper Fish, a beachside kiosk seating around 70. FACT: ABS 2021 recorded St Kilda with 19,490 residents and a median weekly household income of $1,779 (ABS QuickStats).
LOCATALYZE ANALYSIS: the rebuild is the most interesting location decision in this set, because the operator got to redesign the response to a known risk. Beachfront trade in Melbourne is violently weather- and season-dependent. Rather than build one large room and absorb that volatility, the site was rebuilt as three businesses at three price points sharing one address, one kitchen infrastructure and one view. A cold Tuesday and a hot Saturday are served by different parts of the same building.
The trade-offs are capital intensity and complexity: three service models, three labour profiles and a foreshore lease with its own public-land constraints. The lesson: on a high-variance site, stack formats vertically instead of betting the whole floor on one. Our model rates St Kilda 72 out of 100 for restaurants with a GO verdict; see the St Kilda location read.
10. Petaling Street and the Kingsway strip — Glen Waverley — a CAUTION suburb that trades late
Kingsway in Glen Waverley runs a dense, largely Asian dining strip that trades well past the hour most inner-city streets go quiet; Petaling Street at 111 Kingsway serves until midnight, and neighbours including Kingsland Seafood at 97 Kingsway keep similar hours. The strip has also done something Melbourne’s inner suburbs mostly have not: when it ran out of ground floor, it went up. King’s Centre, off Kingsway, stacks seven levels of food and retail including rooftop restaurants.
FACT: ABS 2021 recorded Glen Waverley with 42,642 residents, a median age of 40, an average household size of 2.8 and a median weekly household income of $1,918 (ABS QuickStats). It is by far the largest resident catchment in this article. FACT: our model rates it 61 out of 100 for restaurants — a CAUTION, and one of the lower scores here.
LOCATALYZE ANALYSIS: the score is not wrong, it is coarse. It reads a large, car-dependent, middle-ring centre with high competition density and moderate rent pressure, and returns a cautious average. What it cannot see is that one 400-metre strip inside that suburb has assembled a cuisine cluster, a late trading culture, a station and a resident catchment of 42,000 — a combination almost no inner-city strip can match after 10pm. INFERENCE: the middle ring is where the gap between suburb-level scoring and site-level reality is widest, because the suburbs are physically larger and their centres are more concentrated.
The trade-off is a strip that lives or dies on parking and on the cluster’s continued draw, in a suburb with no walk-up density outside the centre. The lesson: in the middle ring, score the centre, not the suburb. See the Glen Waverley location read.
What the ten have in common
Plotting measured volume against measured shape separates the streets in this article far better than any suburb ranking does. The chart below places the sensors we pulled on two axes: how many people walk past on an average weekday, and how much of that traffic arrives in the evening.
Volume and dinner shape rarely arrive together
The strongest evening shape in the set belongs to Little Bourke Street at 1.93 — the fourth-quietest of the eleven locations. The next two, Melbourne Central at 1.24 and Little Collins Street at 1.15, sit beside a station and a major interchange, where the evening rise is commuters leaving rather than diners arriving. After those comes Errol Street in North Melbourne at 1.14, the second-quietest location we measured. The four retail and office footpaths in the set — both sides of Bourke Street Mall, Collins Street and Degraves Street — all fall below 0.62. LOCATALYZE ANALYSIS: high-volume streets are busy because of offices and shops, and offices and shops close at the hour a dinner restaurant needs its customers. Paying a retail-frontage rent for a dinner business is paying for pedestrians who have gone home.
The best-shaped streets are the ones restaurants built
Little Bourke Street, Errol Street and the Faraday end of Lygon Street all show evening-weighted or flat curves, and all three are streets where hospitality is the reason to visit rather than a service to something else. INFERENCE: the causation most likely runs from the restaurants to the footfall, not the other way round — which means a strip’s evening shape is partly an asset you inherit from the operators who came before you, and partly one you are expected to maintain.
Four of the ten are not really renting passing trade
Flower Drum is upstairs in a lane. Attica is on a suburban road in a suburb of 1,532 people. Moon Dog is in an industrial estate. Pellegrini’s is on the quiet end of a famous street. LOCATALYZE ANALYSIS: each replaced passing trade with a demand-capture mechanism it controls — a cluster, a booking system, a brand, seventy years of habit — and then bought the cheapest, quietest square metres compatible with it. That is the single most repeated move in this article, and it is available to more operators than take it.
Resident income keeps pointing the wrong way
Carlton, at $1,292 a week, is the lowest-income suburb here and one of the strongest restaurant markets. Ripponlea, at $2,023, has 1,532 residents. Fitzroy, at $2,194, scores 84 — but the score averages three strips that behave differently. FACT and analysis in sequence: income measures capacity to spend; it says nothing about how many people are within reach at 7pm, how often they eat out, or whether they are even the intended customer.
Every one of them accepts a named, specific cost
Flower Drum depends on a shared street reputation. Chin Chin carries a high-rent, all-day cost base. Pellegrini’s cannot scale. Cutler competes with peers within two hundred metres. Moon Dog buys every customer. Attica has no fallback daypart. Stokehouse runs three businesses to survive the weather. LOCATALYZE ANALYSIS: an operator who cannot state what their site gives up has not finished the analysis, and the unstated cost tends to arrive in the second year.
Five expensive beliefs about Melbourne locations
“More foot traffic is better”
Only if it arrives when you are selling. Bourke Street Mall carries nearly three times Little Bourke Street’s weekday pedestrians, and only about a quarter more of them between 6pm and midnight. The relevant question is not how many people pass, but how many pass in the hours your kitchen is open and in a state to sit down. We have written separately on why high foot traffic can produce low sales and what foot traffic data does not tell you.
“A high-scoring suburb is a good site”
Fitzroy scores 84 out of 100 for restaurants in our model, the best in Melbourne, and contains three strips with different rents, different customers and different hours. A suburb score is a screening layer — it narrows a shortlist from forty candidates to six. It cannot choose between two shopfronts three hundred metres apart, and it is not designed to.
“The CBD office vacancy means the city is finished”
FACT: Melbourne has the highest CBD office vacancy in the country at 18.9% as at July 2026, against Sydney at 13.3% and Brisbane at 10.2%. FACT: it also has the second-lowest CBD retail vacancy of the major cities at 8.1% in the first half of 2026, against a 10.8% national average (CBRE, via Retailbiz). FACT: ABS 2021 counted 54,941 residents in the suburb of Melbourne, with a median age of 29 (ABS QuickStats). LOCATALYZE ANALYSIS: empty office floors and busy footpaths are not a contradiction. Melbourne’s city centre is a residential suburb with a university population and a visitor economy sitting on top of an office district, and the street economy does not depend on the tower above it.
“Cheap rent is a bargain”
Cheap rent on a street with the wrong shape is a slow, fixed loss. The Lygon Street sensors make the point: 333 metres apart, one carries 5,134 people a day with a 0.94 evening ratio and the other carries 2,034 with 0.50. Rent will be lower at the quieter end, and so will everything else. The comparison that matters is rent per converting cover, and it is the only one worth putting in a spreadsheet.
“Being near competitors is a problem”
For a cuisine people travel for, density is the reason the customer comes: Chinatown, Hopkins Street and Kingsway all work this way, and all three show it in their trading hours. For a convenience format, the same density divides a fixed catchment. The question is never how many competitors, but whether your category travels — and that is answerable before you shortlist a single address.
One change worth watching
FACT: the Suburban Rail Loop East is a 26-kilometre tunnelled line under construction between Cheltenham and Box Hill, with six stations — interchanges at Cheltenham, Clayton, Glen Waverley and Box Hill, and new stations at Monash and Burwood — and a projected opening in 2035. FACT: the City of Melbourne forecasts on-site jobs across the municipality rising 32% to more than 675,300 by 2043, with Food and Beverage Services adding around 18,700 of them. LOCATALYZE ANALYSIS: both are long-dated, and a lease signed in 2026 will be renewed before either lands. INFERENCE: the near-term effect of an announced station is on rent expectations, not on covers — landlords price the future before operators can trade it.
Read a Melbourne street’s shape
The tool below carries the same August 2026 data used throughout this article. Pick a location to see its measured hourly curve, its weekday and weekend volumes, its evening-to-lunch ratio, and the formats its shape actually supports. Every figure is the published City of Melbourne count, averaged by us across the month.
Measured footfall · August 2026
What shape is this street?
Eight City of Melbourne sensor locations, averaged across a full month. Pick one to see when its pedestrians actually arrive — and what that shape can support.
Little Bourke St, Chinatown
- Pedestrians per weekday6,960
- Evening ÷ lunch1.93
- Peak hour6pm
Darker bars are the 6pm–midnight dinner window. Bar heights are relative to this location’s own busiest hour, so compare shapes here and volumes in the figures above.
| Hour | Pedestrians |
|---|---|
| 6am | 14 |
| 7am | 52 |
| 8am | 97 |
| 9am | 105 |
| 10am | 178 |
| 11am | 298 |
| 12pm | 537 |
| 1pm | 496 |
| 2pm | 375 |
| 3pm | 359 |
| 4pm | 385 |
| 5pm | 625 |
| 6pm | 784 |
| 7pm | 740 |
| 8pm | 610 |
| 9pm | 521 |
| 10pm | 420 |
| 11pm | 213 |
The only location we measured where evening is nearly twice lunch, and the peak hour is 6pm. A third of Bourke Street Mall’s people, and the right third for a dinner restaurant.
Locatalyze calculation from the City of Melbourne Pedestrian Counting System, 1–31 August 2026. Sensors measure footpath movement, not entries or spend. August is a Melbourne winter month, so volumes sit below an annual average; the shapes are far more stable than the levels.
The Melbourne pre-lease checklist
Twelve checks, in the order we would do them. Several are only possible in Melbourne, and it would be strange not to use them.
Twelve checks before you sign a Melbourne hospitality lease
Allow two weekends and one full working day
Testing a site of your own
Everything above came from public evidence: an open sensor dataset, census tables, property market reporting, government announcements and the venues’ own published information. For one address inside the City of Melbourne that is a genuinely good weekend’s work, and we would encourage it. It stops being a weekend when the site is in Preston or Glen Waverley, where no counts exist, or when you are comparing six addresses across three suburbs against a lease deadline.
That is the work Locatalyze does. You enter an address, a business type and a monthly rent; the platform assembles the demand, competition, demographic and rent-pressure evidence for that specific frontage and returns a scored, sourced read with the reasoning shown. Financial figures are computed deterministically and never written by a language model — our methodology sets out where that boundary sits. For shortlisting across Melbourne, the Melbourne location hub and the Melbourne restaurant guide are the screening layer; the report is the decision layer.
Check the block, not the suburb
Suburb scores narrow a shortlist. Locatalyze reads one specific Melbourne frontage for demand, competition, catchment and rent pressure, and shows the evidence behind every number.
Analyse a Melbourne address freeMethod, evidence and limits
Pedestrian figures. We queried the City of Melbourne’s Pedestrian Counting System (counts per hour) through its public API for every reading between 1 and 31 August 2026 at eleven sensor locations. For each location we summed counts by calendar day, then took the mean across the 21 weekdays and the 10 weekend days in the month. Hourly profiles are the mean count for each hour across the same days. The evening-to-lunch ratio divides the summed 6pm–midnight profile by the summed 11am–3pm profile. Distances between sensors are great-circle calculations from the coordinates published with each sensor. August is a Melbourne winter month, so absolute volumes will be lower than an annual average; the ratios are the point, and they are far more stable than the levels.
Selection. Ten venues were chosen to span distinct location strategies, not to rank quality. Each had to be currently trading, publicly documented, and instructive about a decision an operator can actually make. Three sit in the CBD because that is where the counts exist, and we would rather over-weight the measurable part of the city than assert numbers for the rest of it.
Limits, stated plainly. We do not have any venue’s revenue, rent, margins, covers or profitability, and we have not estimated them. We do not claim any venue succeeds because of its location — hospitality outcomes are over-determined, and food, service, capital and management sit inside every one. Sensors measure footpath movement, not entries, not spend, and not intent; a person walking to a train is counted the same as a person walking to a table. Suburb scores are model outputs on the August 2026 vintage and move as the underlying data moves. Where a figure could not be verified, it is absent rather than approximated.
Locatalyze is decision-support for location choice. Nothing here is legal, valuation, financial or investment advice, and no venue named in this article is a customer, partner or sponsor. Last checked 6 September 2026.
Sources
Primary and industry sources
Related Locatalyze research
Frequently asked questions
About the author
Locatalyze Research Team
Location intelligence, Locatalyze
The Locatalyze research team builds the location-scoring models behind the platform and writes up what the evidence shows for Australian operators.
Tools first — then a full report for your address
Free rent, viability, and break-even checks. Upgrade when you are ready for competitors, map, and numbers for a specific site.
No signup required for tools