St Kilda insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
Location score
72
out of 100
Recommendation
PROCEED
Promising fit, subject to normal due diligence
71
Café
72
Restaurant
72
Retail
Businesses analysed30
Cache updated27 June 2026
Enginev7.4.0
Medium confidence
30 businesses sampled near St Kilda centre (last refreshed 27 June 2026); suburb scores use Locatalyze engine v7.4.0. Suburb-centre snapshots for St Kilda — validate at your lease address before signing.
One-line read on what this precinct means for operators.
St Kilda trades coastal throughput plus nightlife pulses — commercial viability swings on whether your model survives summer peaks, event nights, and inconsistent weekday office gravity.
2. Location intelligence snapshot
Figures below combine Locatalyze five-factor inputs with precinct editorial interpretation — always validate on-site with trade-area counts before signing a lease.
Demand strength (model)
9/10 — customer intent density for this precinct
Foot traffic intensity (modelled)
Very high — dense daytime + strong visitor-driven pulses
Competition intensity
Moderate — room for distinct offers
Commercial rent pressure
Material — negotiate incentives and trade-area proof
Why people move through this precinct, how spending behaves, and how dayparts shape revenue.
Spend mixes visitor intent, hospitality shifts, and selective professional commuters — daypart strategy matters more than in purely residential strips.
Retail wins where window narrative converts impulse on Acland/Fitzroy corridors; operators relying only on evening trade inherit roster volatility.
4. Business-type performance
Engine scores plus operator rationale — commercial viability only.
Café / specialty coffee71/100
Engine café line 71/100 weights demand 9/10 and commercial rent pressure 6/10 — stronger where commuter throughput is predictable and competition isn’t purely generic.
Full-service restaurant72/100
Restaurant line 72/100 lifts when tourism 8/10 supports dinner trade and seasonality 4/10 stays manageable for roster planning.
Independent retail72/100
Retail line 72/100 responds to demand × tourism blend — wins where window visibility and category gaps align with walk-by intent.
Services / fitness (proxy)72/100
Services / fitness proxy 72/100 blends retail + hospitality signals — use for gym, salon, and appointment formats where repeat locals matter.
5. Competition & saturation analysis
Where categories crowd out entrants and where disciplined positioning still clears margin.
Saturation concentrates on hospitality strips — differentiation beats louder signage.
Gap formats appear where cuisines are under-represented relative to visitor diversity — execution risk stays high near nightlife friction.
6. Street-level intelligence
Micro-zones inside the suburb — not uniform throughput.
Acland + cafe precinct
Performance: Peak visitor throughput
Operator note: Rent for visibility — manage noise compliance.
Fitzroy Street spine
Performance: Night-trade weighted
Operator note: Sound management and security optics dominate approvals.
St Kilda insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
10. Commercial FAQ library
Structured for search and AI citation — operator viability only (no residential rental advice).
Is St Kilda a good place to open a restaurant near the beach?
St Kilda can be strong for restaurants when your model survives seasonal cash-flow swings and trades well across night hospitality pulses as well as daytime coastal visitation. Commercial viability is driven by mixed visitor intent, local residents, and Melbourne-wide destination trips — especially along Fitzroy Street and near foreshore draws — but lease negotiations must reflect quieter midweek realities outside peak tourism windows. Operators fail when they budget only for sunny Saturdays or assume uniform dinner demand across all blocks. Practical insight: separate summer roster peaks from winter staffing baselines. Strategic takeaway: St Kilda rewards restaurants that own a cuisine wedge and manage volatility deliberately.
When is foot traffic strongest in St Kilda — and what drives it?
Peaks typically cluster around warm-weather weekends, evening hospitality corridors, and event-linked nights, with weekday lift near workplaces and health/education adjacencies depending on micro-location. Foot traffic is partly destination-driven, meaning spending intent can spike fast but also thin quickly when weather or competing precincts steal share. Understanding customer flow requires separating beach-adjacent impulse from Fitzroy Street nightlife rhythm — they are not interchangeable. Practical insight: measure counts across season and weekday for your exact segment. Strategic takeaway: treat St Kilda as multiple pulse economies stitched together — averages obscure lease risk.
Is St Kilda oversaturated for cafés and casual dining?
Saturation is real in generic casual categories, yet gaps remain where menus reflect distinct cuisines, credible beverage programs, or disciplined daytime throughput models that survive winter. Oversaturation hurts copycats fastest because substitution is easy — diners can slide to nearby precincts with marginal friction. Winning entrants bring crisp positioning and operational clarity: sound management for late trade, robust takeaway workflows, and marketing that converts tourists into repeats where possible. Strategic takeaway: “oversaturated” is a warning for undifferentiated operators — not a blanket ban on competent specialists.
Which streets and precincts in St Kilda perform best for hospitality?
Acland Street and adjacent café precincts capture strong visitor throughput but carry tourism volatility and noise-compliance realities. Fitzroy Street behaves like a nightlife spine — peak patterns skew late; security and acoustic diligence matter. Residential pockets off-strip trade more like neighbourhood services — lower naive foot traffic, higher loyalty potential if marketing is deliberate. Avoid treating “St Kilda” as uniform: micro-location determines whether you monetise beach impulse, bar trade, or quiet locals. Strategic takeaway: pick the street that matches your daypart engine — don’t borrow prestige from the wrong corridor.
Who spends money in St Kilda — tourists vs locals?
Spend mixes Melbourne-wide visitors, bay locals, and city-going workers depending on block — coastal precincts skew visitor-heavy on weekends, while inland connectors behave more like stable neighbourhood trade with seasonal amplification. Customer behaviour can swing seasonally and weather-linked, which impacts roster planning for hospitality more than for essentials retail. Retail concepts should assume curiosity visits convert only when SKU clarity exists; hospitality should assume repeats must be earned through consistency. Strategic takeaway: model tourist uplift as a bonus, not the baseline rent payer.
What are the biggest commercial risks for new venues in St Kilda?
Key risks include seasonality, night-economy friction (noise complaints, compliance costs), and substitution to neighbouring strips when differentiation slips. Lease risk compounds when operators assume coastal branding equals stable turnover — winter Wednesday still exists. Labour volatility rises with late-night formats; insurance and security optics matter on Fitzroy Street corridors. Mitigation is scenario planning: baseline cash flow without peak tourism, conservative staffing models, and acoustic/design discipline upfront. Strategic takeaway: St Kilda punishes romantic forecasting — reward disciplined operators.
St Kilda vs Prahran for nightlife-led hospitality — which fits my concept?
St Kilda often carries stronger coastal tourism pulses and late-night energy on hospitality spines; Prahran trades more inner-south strip prestige and tighter Chapel-adjacent substitution. Choose St Kilda when your playbook monetises weekend influx and event-linked evenings credibly; choose Prahran when your brand benefits from Stonnington adjacency and commuter-linked theatre — understanding your labour model and acoustic constraints matters more than suburb hype. Strategic takeaway: compare micro-blocks and trading outcomes, not postcards.
Would a café “work” in St Kilda year-round?
A café can work year-round if your economics survive winter midweeks and you capture commuter and local ritual outside pure beach tourism. Seasonality doesn’t kill competent cafés — it kills menus built only for sunny Saturdays. Operators win with pickup clarity, indoor comfort, and weekday employer ties (corporate catering, reliable opening hours). Strategic takeaway: treat summer as upside — hardcode viability against quieter seasons.
Is retail demand strong enough for a boutique store in St Kilda?
Boutique retail can work when your offer matches destination intent — swim, leisure, gifts tied to coastal ritual — or when you operate appointment-led experiences that don’t rely solely on naive walk-past. Competition from online and nearby precincts raises the bar for storytelling and inventory turns. Practical insight: validate weekly repeat visits and basket economics before committing to trophy frontage. Strategic takeaway: retail viability is SKU-discipline first, foot traffic second.
What business categories are underrated in St Kilda?
Underrated wedges include high-quality fast formats feeding commuter mornings, health services aligned to active coastal lifestyles, and distinct regional cuisines absent from immediate substitution sets. Operators chase instagrammable brunch while weekday efficiency gaps persist — especially consistent lunch that clears wage lines. Strategic takeaway: solve repetitive problems residents still complain about after tourism goes home.
What’s the biggest leasing mistake operators make in St Kilda?
Signing leases priced on peak-season storytelling without modelling winter cash flow — especially for venues dependent on outdoor dwell. Another mistake: underestimating compliance and acoustic remediation costs near nightlife corridors. Fix with conservative ramp assumptions and tenant incentives that acknowledge seasonality. Strategic takeaway: negotiate rent like you’ll survive February — because you must.
How do I evaluate St Kilda using Locatalyze instead of guesswork?
Start with suburb-level signals for hospitality and retail fit, then graduate to address-level competitor mapping and lease benchmarking so you understand substitution within minutes — not kilometres — of your door. Locatalyze is built for commercial viability screening: demand strength, competition density, tourism dependency context, and trading-risk framing — aligned to operators, not residential commentary. Strategic takeaway: combine precinct intuition with door-specific evidence before you execute a lease.
Locatalyze scores are engine-derived from demand strength, commercial rent pressure, competition density, seasonality risk, and tourism dependency — each 1–10 — rolled into business-type lines and composite verdicts. This report is commercial location intelligence for operators, not residential market commentary.
What the model is seeing
Café 71, restaurant 72 and retail 72 sit within 1 points. The model is not choosing a format. The suburb verdict is PROCEED at 72/100.
No factor is in a tight band. Demand is 9/10, rent pressure 6/10, competition 5/10, and seasonality 4/10. The verdict comes from the weighted blend, not from one red flag.
Tourism dependency is 8/10. Restaurant and retail scores include that visitor component. The café score does not. Do not annualise a holiday week.
Elwood is the nearest scored suburb, about 1.3 km away. Demand 9/10 versus 7/10. Both figures are suburb scores, not a walk between the two shopfronts.
A competitor snapshot lists 30 venues. That is an observation from the snapshot, not evidence the suburb is under-supplied.
This is a reading of the five factors and three format scores on this page. It is not a rent quote, a competitor count, or a reason to sign a lease.
How to read these scores
Composite 72/100. The format scores sit within 1 points, so this panel does not pick a format.
Source
Locatalyze engine v7.4.0 plus cached local competitor evidence
Freshness
Competitor cache refreshed 27 June 2026
Confidence
Medium - 30 businesses sampled
Limitation
St Kilda scores screen the suburb, not the lease. The paid report tests frontage, rent, nearest competitors, and break-even at your exact address.
Evidence freshness
Scores
Engine v7.4.0; suburb-level model
Competition
Google Places cache refreshed 27 June 2026
Rent
No sourced asking-rent series — obtain current listings
Demographics
ABS Census 2021 is cited only where this page states a count. A score is not a census figure.
Mini location report — St Kilda
Restaurant opportunity snapshot
PROCEED band for restaurant operators in St Kilda.
Restaurant opportunity score
72/100
Demand strength
9/10
Rent pressure
Moderate (6/10)
Competition density
5/10
Financial model — unlock at your address
Suburb-level estimates only. Your full report models P&L from your lease address, rent, and format.
🔒Est. monthly revenue range
Modelled at your address from rent, ticket and demand — not a suburb average
🔒Break-even customers per day
Calculated from your rent, staffing, and average ticket at your exact address
🔒Payback period on fit-out
Months to recover setup costs at base-case revenue
🔒Rent-to-revenue ratio
Whether the lease is sustainable at modelled trade levels
See if the numbers work at your rent
Run a free analysis at your St Kilda address. Unlock modelled P&L, break-even, and scenarios from $29.
Demand, rent, competition, seasonality, and tourism — scored and weighted for Australian commercial operators.
9/10
Demand
6/10
Rent cost
5/10
Competition
4/10
Seasonality
8/10
Tourism dep
Business-Type Scores
How each format performs
Café / Specialty Coffee71
Full-Service Restaurant72
Independent Retail72
Scores use engine-derived weights: cafés weight demand and rent most heavily; restaurants factor tourism; retail factors tourism and demand equally.
Analyst Notes — St Kilda
What the data says about this location
1
Demand 9/10: coastal premium with strong tourist and residential mix.
2
Seasonality 4/10: summer peaks 40% above winter; operators must plan for trough months.
Decision tree
St Kilda carries the strongest brand-recognition of any Melbourne bayside precinct — beach, Luna Park, and layered tourist flow on top of a dense coastal-resident catchment. Demand scores 9/10; rent pressure 6/10; competition 5/10; tourism 8/10. Composite location score is 72/100 with a PROCEED verdict for cafés at 71/100 — opportunity is real, but more new operators have closed inside 24 months on Acland Street and Fitzroy Street than on comparable inner-Melbourne strips. Rococo St Kilda, Galleon Cafe, Monk Bodhi Dharma, Donovans, and Republica St Kilda Beach already own recommendation paths. The trap is summer-baseline budgeting on beachfront rent, or treating Acland Street tourist browse as interchangeable with Fitzroy Street evening trade.
Treating the precinct as one market is the dominant failure mode.
The competitor snapshot surfaces Rococo St Kilda, Galleon Cafe, Monk Bodhi Dharma, Lady Of St Kilda, Republica St Kilda Beach, Donovans, Stokehouse St Kilda, and The Local Taphouse within the core trade area. Your model must clear winter-month P&L individually — not average December trading across twelve months.
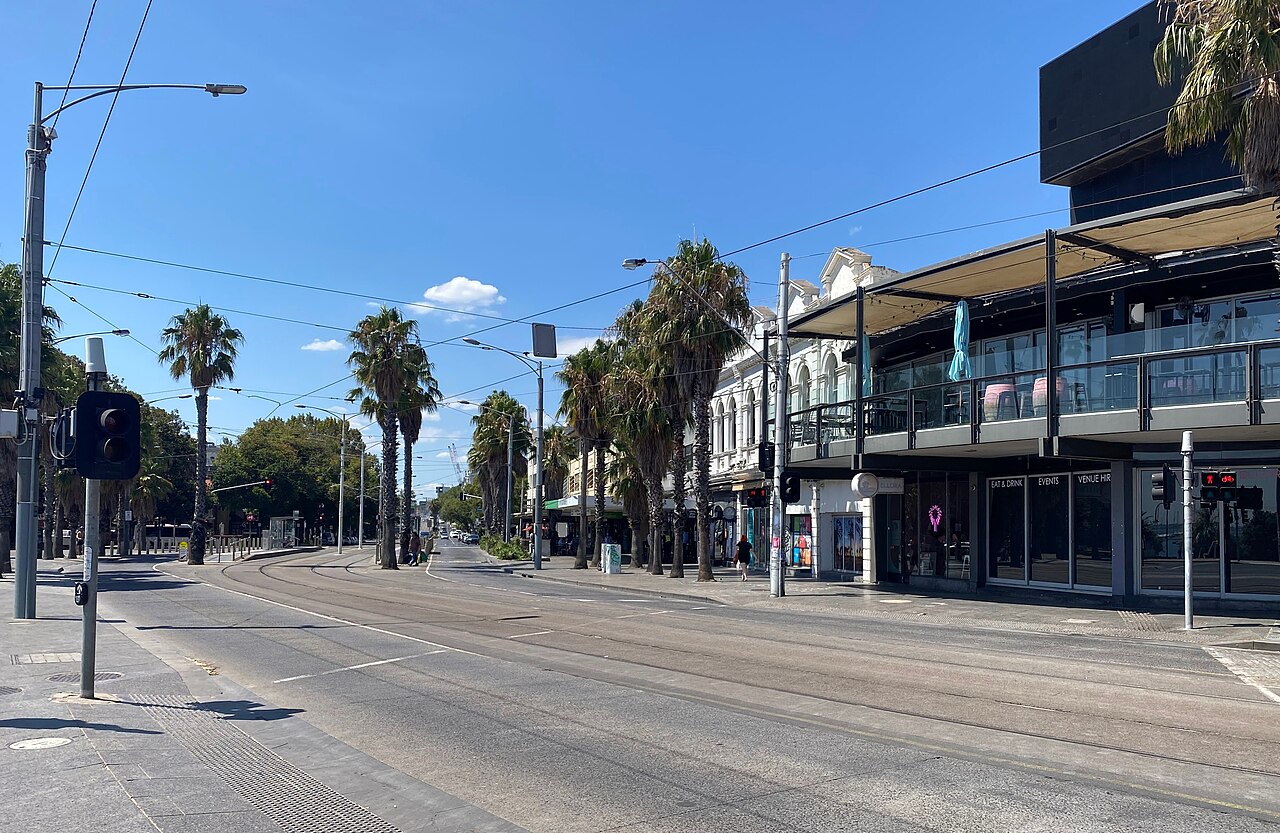
Fitzroy Street south and the Esplanade carry summer peaks 35–45% above winter trough — Acland tourist browse and Fitzroy evening trade are different operating systems. Photo: Donaldytong, CC BY-SA 3.0 (Wikimedia Commons)
If you are considering a café in St Kilda
Pick street before menu.
Decision: resident-led specialty on Carlisle or Fitzroy north — or Esplanade café with explicit trough budgeting.
If you are considering a full-service restaurant
Donovans, Stokehouse, Republica, and Topolino's prove the band; operators must model winter months at trough, not summer peak.
Fitzroy Street north and Carlisle suit considered neighbourhood dining and wine-led formats with lower seasonality exposure than beachfront — Cicciolina and Sister of Soul set the resident-and-visitor blend benchmark.
Acland Street full-service dining faces tourist conversion challenge — high foot traffic, weaker loyalty conversion, and reputation overhead from dense mid-tier incumbents.
Decision: evening restaurant on Fitzroy south with 12–15 months conservative capital and trough-month lease coverage — or walk away from summer-peak financial modelling on beachfront rent.
If you are considering a bar or late-trading venue
Fitzroy Street carries among Melbourne's densest nightlife catchments — Friday and Saturday 18:00–midnight is the revenue engine. The Local Taphouse and late-trading venues on the southern stretch absorb resident and visitor evening flow.
Carlisle Street and Fitzroy north suit wine bar and cocktail formats with lower seasonality than Esplanade — tighter fit-out envelope than full-service dining, resident catchment absorbing mid-week trade.
Verify licensing and noise constraints — residential complaints cap hours on some blocks; model revenue without midnight upside if complaints history exists on the tenancy.
Decision: evening-loaded bar on Fitzroy south or north with multi-daypart revenue — not single-window format at Acland or Esplanade prime rent.
If you are considering specialty retail or allied services
Destination retail with strong brand — specialty fashion, considered surf-and-coastal, design with Melbourne-product story — works on Fitzroy Street when product drives deliberate visits, not browsing-traffic conversion alone.
Acland specialty food retail can work for established operators with credentials — heritage cake-shop identity anchors the strip, but non-food formats face conversion challenge.
Decision: appointment-led services on cross-streets — or destination retail with brand pull on Fitzroy north. Not walk-in retail expecting Acland tourist conversion rates.
Reading Fitzroy Street versus Acland Street versus Carlisle
Fitzroy Street south and Esplanade carry beach-adjacent visitor flow and evening licensing density — summer peaks 35–45% above winter trough on revenue. Acland Street carries tourist daytime browse with high foot traffic but 4–6% conversion on many frontages — rent does not support sustainable margin at realistic conversion. Carlisle and Fitzroy north carry resident-led rhythm with materially softer seasonality.
The official seasonality score of 4/10 averages across the precinct and materially understates beachfront divergence — position-level modelling is mandatory.
Who should invest here — and who should walk away
Invest if your financial model clears winter-month P&L at quoted rent before signing — trough budgeting, not summer baseline.
Invest if you match street to format rhythm: Fitzroy south for evening, Carlisle for resident specialty, cross-streets for allied services.
Invest if you carry marketing reserve for 12–18 month reputation curve against dense incumbent field.
Walk away if you depend on stable year-round volume without seasonal compression — winter weekday trade can fall 30–40% from summer peaks on beachfront.
Walk away if you treat Acland and Fitzroy as interchangeable or buy into historical St Kilda narrative without position-level flow validation.
What to verify before you sign a St Kilda lease
Which street your tenancy sits on — Fitzroy south, Acland tourist, Fitzroy north/Carlisle resident, or cross-street allied.
June and July covers versus December-January on your specific frontage — decide if trough months clear labour at quoted rent.
Nearest named competitors within 300m — Rococo, Galleon, Monk Bodhi Dharma, Donovans, Republica, or The Local Taphouse.
Browse-to-revenue conversion if Acland or Esplanade daytime — count pedestrians versus paying customers, not foot traffic alone.
Liquor licensing and noise history if bar format — model hours actually achievable, not theoretical.
Marketing reserve in capital plan — reputation curves run longer than less dense precincts.
Zone-by-zone breakdown
Fitzroy Street south and Esplanade
Beach-adjacent highest summer visitor flow, evening-loaded rhythm, 35–45% summer-winter revenue divergence. Best for trough-budgeted evening dining, late-trading venues, destination retail with brand.
Acland Street tourist stretch
Heritage cake-shop identity, weekend tourist daytime flow, pedestrianised frontage. Best for established specialty food, destination concepts with credentials — poor fit for generic café expecting conversion.
Fitzroy Street north and Carlisle Street
Resident-catchment-led rhythm, lower seasonality exposure. Best for wine bars, specialty café, considered neighbourhood dining.
Apartment cross-streets
Resident-adjacent, limited visitor flow. Best for allied health, professional services, appointment-based formats.
Operator Intelligence
10 dimensions — what matters most here
Scored 1–10 from an operator perspective: higher always means better. Each dimension includes the reasoning behind the score.
Foot Traffic VolumeCritical
Acland and Fitzroy Streets generate among Melbourne's highest pedestrian counts outside CBD — layered tourist, resident, and nightlife flow.
8/10
Hospitality DensityCritical
Among Melbourne's most hospitality-saturated precincts — intense competition across every daypart.
9/10
Retail ViabilityCritical
Fitzroy boutiques and Acland precinct support specialist retail; tourist volume adds upside, residents provide baseline.
7/10
Demographic AlignmentImportant
Mixed renters, creatives, long-term residents, tourists — format must account for diversity.
7/10
Repeat Customer PotentialImportant
Tourist volume dilutes repeat concentration; resident loyalty exists but is heavily competed for.
6/10
Entry EaseImportant
Premium rent, intense competition, high fit-out expectations — expensive and risky entry.
3/10
Rent SustainabilityImportant
Acland and Fitzroy command among inner-south's highest rents — multi-daypart or high average spend required.
4/10
Transit & AccessibilitySupporting
Multiple tram routes; accessible to large inner-Melbourne catchment.
8/10
Tourism ContributionSupporting
Premier tourist destination — Luna Park, beach, Esplanade; adds volume and seasonal volatility.
8/10
Growth TrajectorySupporting
Mature precinct — opportunity is execution within proven market, not rising-suburb upside.
Prahran Chapel Street carries more reliable year-round volume at comparable secondary-street rent. St Kilda offers stronger weekend and tourist peaks with more pronounced seasonality.
South Yarra carries wealthier demographic and higher average spend. St Kilda has more foot traffic volume but lower average spend and heavier competition at entry tier.
Decision framework
St Kilda rewards operators who budget against the trough, match format to street rhythm, and validate position-level flow against historical narrative. Dominant failure pattern is summer-peak modelling on beachfront rent with Acland-Fitzroy conflation.
Operators with trough-budgeted models, marketing reserve, and product differentiation find St Kilda productive. Generic mid-tier formats expecting reputation to drive volume consistently underperform.
St Kilda suburb-level scoring tells you high demand and tourism anchor but not position-level seasonality curve, browse-to-revenue conversion on your frontage, or whether the tenancy sits in a still-strong stretch versus post-2010 identity transition. Locatalyze runs address-level analysis surfacing seasonality, conversion, and operating envelope at the position you are evaluating.
St Kilda insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
More questions about opening in St Kilda
How material is seasonality on a beachfront position?
Material. Summer peaks run 35–45% above winter troughs on beachfront-adjacent positions. Trough-budget financial models and winter variable-cost compression are mandatory.
Is Acland Street viable for a new café?
Difficult for generic formats. Tourist browse conversion is low relative to foot traffic. Strong product credentials and 12–18 month reputation capital can clear; undifferentiated cafés consistently underperform.
How does Fitzroy Street compare to Acland Street?
Different precincts. Fitzroy south is evening and beach-adjacent; Fitzroy north is resident-led; Acland is tourist daytime with high traffic but low conversion. Format must follow the street.
Has Acland Street pedestrianisation changed the environment?
Mixed outcomes. Validate position-level flow rather than relying on pre- or post-pedestrianisation reputation alone.
Methodology: Scores are engine-derived from five observable inputs (demand strength, rent pressure, competition density, seasonality risk, tourism dependency — each 1–10). These feed into business-type-specific weighted composites via a single scoring engine used across all markets. Scores are relative estimates calibrated across all Melbourne suburbs — a score of 80 indicates materially better conditions than 65; it is not a success probability or guarantee.
Frequently Asked Decision Questions
Have a specific address in St Kilda?
Run a free location check — named competitors, a rent benchmark, and location score, data confidence, and proceed / verify / avoid recommendation — for any St Kilda address.
St Kilda insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
·4.4★ and 3,629 reviews — customers actively recommend this restaurant.
·Review volume 113% above peer average (1,702).
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
If you are opening nearby: Republica St Kilda Beach is the benchmark restaurant here — their 4.4★ and 3,629 reviews beat the 1,702-review peer average — $$ positioning is validated by review depth in this catchment.
·4.6★ with 1,951 reviews — repeat local demand, not one-off visits.
·0.2★ above the 4.4★ average among top local peers.
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
If you are opening nearby: The Local Taphouse (Dominant) shows what execution looks like at this score tier — 4.6★ with 1,951 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment.
·4.3★ and 3,042 reviews — customers actively recommend this restaurant.
·Review volume 72% above peer average (1,767).
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
If you are opening nearby: Rococo St Kilda (Dominant) shows what execution looks like at this score tier — their 4.3★ and 3,042 reviews beat the 1,767-review peer average — $$ positioning is validated by review depth in this catchment — 259m from centre — frontage on the walkable strip matters.
4. Topolino's
★★★★☆ 4.4 (2,154 reviews) · $$ · 883m from centre
72 · Established
·4.4★ and 2,154 reviews — customers actively recommend this restaurant.
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
If you are opening nearby: 4.4★ with 2,154 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment — For new entrants: Focus on a specific occasion (date night, quick lunch, or group dining) that Topolino's does not dominate.
5. Sister of Soul
★★★★☆ 4.3 (2,065 reviews) · $$ · 271m from centre
78 · Dominant
·4.3★ and 2,065 reviews — customers actively recommend this restaurant.
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
·Central location (271m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: Sister of Soul (Dominant) shows what execution looks like at this score tier — 4.3★ with 2,065 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment — 271m from centre — frontage on the walkable strip matters.
Possible market opportunities
Derived from venue counts and formats in our Google Places snapshot — not a guarantee of demand at your exact address.
Medium confidenceTourist-friendly lunch spot with local produce story
Reason: Tourism dependency is elevated — visitors want authentic local food without fine-dining price tags.
Who wins in St Kilda — Cafés
Ranked by success score (rating, review depth, centrality) within ~800m of the suburb centre.
What winners have in common
·7 of 10 top venues sit at 4.3★+ — customers reward consistent execution, not novelty alone.
·Review depth averages 1,599 — operators with under 150 reviews read as unproven next to incumbents.
·Typical positioning is $$ (9 venues report Google price tiers).
·5 benchmark operators combine 4.4★+ ratings with 150+ reviews — new entrants need a clear niche, not a me-too menu.
·4.8★ with 2,127 reviews — repeat local demand, not one-off visits.
·0.5★ above the 4.3★ average among top local peers.
·Review volume 38% above peer average (1,540).
If you are opening nearby: Lady Of St Kilda is the benchmark café here — their 4.8★ and 2,127 reviews beat the 1,540-review peer average — $$ positioning is validated by review depth in this catchment — 301m from centre — frontage on the walkable strip matters.
·4.3★ and 3,042 reviews — customers actively recommend this café.
·Review volume 112% above peer average (1,438).
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
If you are opening nearby: Rococo St Kilda (Dominant) shows what execution looks like at this score tier — their 4.3★ and 3,042 reviews beat the 1,438-review peer average — $$ positioning is validated by review depth in this catchment — 259m from centre — frontage on the walkable strip matters.
·4.2★ and 2,926 reviews — customers actively recommend this café.
·Rating sits below the 4.4★ peer average — volume or convenience may be doing the work.
·Review volume 102% above peer average (1,451).
If you are opening nearby: Abbey Road Cafe (Dominant) shows what execution looks like at this score tier — 4.2★ with 2,926 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment — 242m from centre — frontage on the walkable strip matters.
4. Galleon Cafe
★★★★½ 4.6 (909 reviews) · $$ · 239m from centre
85 · Dominant
·4.6★ with 909 reviews — repeat local demand, not one-off visits.
·0.2★ above the 4.4★ average among top local peers.
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
If you are opening nearby: Galleon Cafe (Dominant) shows what execution looks like at this score tier — 4.6★ with 909 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment — 239m from centre — frontage on the walkable strip matters.
5. Monk Bodhi Dharma
★★★★½ 4.6 (845 reviews) · $$ · 799m from centre
77 · Established
·4.6★ with 845 reviews — repeat local demand, not one-off visits.
·0.2★ above the 4.4★ average among top local peers.
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
If you are opening nearby: 4.6★ with 845 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment — For new entrants: Monk Bodhi Dharma is beatable on pastry-forward with a limited hot menu — avoid matching incumbents' full menu breadth.
Who wins in St Kilda — Retail
Ranked by success score (rating, review depth, centrality) within ~1500m of the suburb centre.
What winners have in common
·7 of 10 top venues sit at 4.3★+ — customers reward consistent execution, not novelty alone.
·Most winners sit within 400m of the suburb centre — frontage on the walkable strip matters.
·4.8★ with 245 reviews — repeat local demand, not one-off visits.
·0.3★ above the 4.5★ average among top local peers.
·Review volume 341% above peer average (56).
If you are opening nearby: Alter It St Kilda is the benchmark retail here — their 4.8★ and 245 reviews beat the 56-review peer average — 306m from centre — frontage on the walkable strip matters.
2. Eclectico
★★★★½ 4.7 (94 reviews) · 255m from centre
76 · Established
·4.7★ and 94 reviews — customers actively recommend this retail.
·0.2★ above the 4.5★ average among top local peers.
·Central location (255m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: their 4.7★ and 94 reviews beat the 72-review peer average — 255m from centre — frontage on the walkable strip matters — For new entrants: Niche or service-led retail beats another generalist shelf near Eclectico.
3. Danish Blue St Kilda
★★★★½ 4.6 (96 reviews) · 921m from centre
65 · Established
·4.6★ and 96 reviews — customers actively recommend this retail.
·Review volume 33% above peer average (72).
If you are opening nearby: their 4.6★ and 96 reviews beat the 72-review peer average — For new entrants: Niche or service-led retail beats another generalist shelf near Danish Blue St Kilda.
4. Chakra
★★★★½ 4.6 (79 reviews) · 266m from centre
70 · Established
·4.6★ rating beats the typical retail baseline in this catchment.
·Central location (266m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: 266m from centre — frontage on the walkable strip matters — For new entrants: Niche or service-led retail beats another generalist shelf near Chakra.
5. Fully Promoted St Kilda
★★★★½ 4.7 (57 reviews) · 506m from centre
67 · Established
·4.7★ rating beats the typical retail baseline in this catchment.
·0.2★ above the 4.5★ average among top local peers.
If you are opening nearby: For new entrants: Niche or service-led retail beats another generalist shelf near Fully Promoted St Kilda.
Possible market opportunities
Derived from venue counts and formats in our Google Places snapshot — not a guarantee of demand at your exact address.
Medium confidenceService-led retail (phone repair, alterations, or plant studio)
Reason: Product-only retail is crowded online — hands-on services tied to a high-street address defend against e-commerce.