Gordon insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
Location score
61
out of 100
Recommendation
VERIFY
Potentially viable — important checks remain
65
Café
60
Restaurant
56
Retail
Businesses analysed30
Cache updated27 June 2026
Enginev7.4.0
Medium confidence
30 businesses sampled near Gordon centre (last refreshed 27 June 2026); suburb scores use Locatalyze engine v7.4.0. Suburb-centre snapshots for Gordon — validate at your lease address before signing.
Café leads at 65/100, 9 points above retail at 56/100. The gap is real but modest — it is not a settled format choice. The suburb verdict is VERIFY at 61/100.
Rent pressure at 7/10 is the constraint. Demand is 8/10 and competition is 6/10. The page does not turn that pressure score into a dollar rent.
Killara is the nearest scored suburb, about 1.4 km away. Competition 6/10 versus 4/10. Both figures are suburb scores, not a walk between the two shopfronts.
A cited count is on this page. It is a suburb baseline, not a forecast and not a rent quote.
This is a reading of the five factors and three format scores on this page. It is not a rent quote, a competitor count, or a reason to sign a lease.
How to read these scores
Composite 61/100; Café 65/100. Use this as an early location verdict before lease diligence.
Source
Locatalyze engine v7.4.0 plus cached local competitor evidence
Freshness
Competitor cache refreshed 27 June 2026
Confidence
Medium - 30 businesses sampled
Limitation
Gordon scores screen the suburb, not the lease. The paid report tests frontage, rent, nearest competitors, and break-even at your exact address.
Evidence freshness
Scores
Engine v7.4.0; suburb-level model
Competition
Google Places cache refreshed 27 June 2026
Rent
No sourced asking-rent series — obtain current listings
Demographics
ABS Census 2021 is cited only where this page states a count. A score is not a census figure.
Mini location report — Gordon
Café opportunity snapshot
VERIFY band for café operators in Gordon.
Also scored: Restaurant 60 · Retail 56
Café opportunity score
65/100
Demand strength
8/10
Rent pressure
Elevated (7/10)
Competition density
6/10
Financial model — unlock at your address
Suburb-level estimates only. Your full report models P&L from your lease address, rent, and format.
🔒Est. monthly revenue range
Modelled at your address from rent, ticket and demand — not a suburb average
🔒Break-even customers per day
Calculated from your rent, staffing, and average ticket at your exact address
🔒Payback period on fit-out
Months to recover setup costs at base-case revenue
🔒Rent-to-revenue ratio
Whether the lease is sustainable at modelled trade levels
See if the numbers work at your rent
Run a free analysis at your Gordon address. Unlock modelled P&L, break-even, and scenarios from $29.
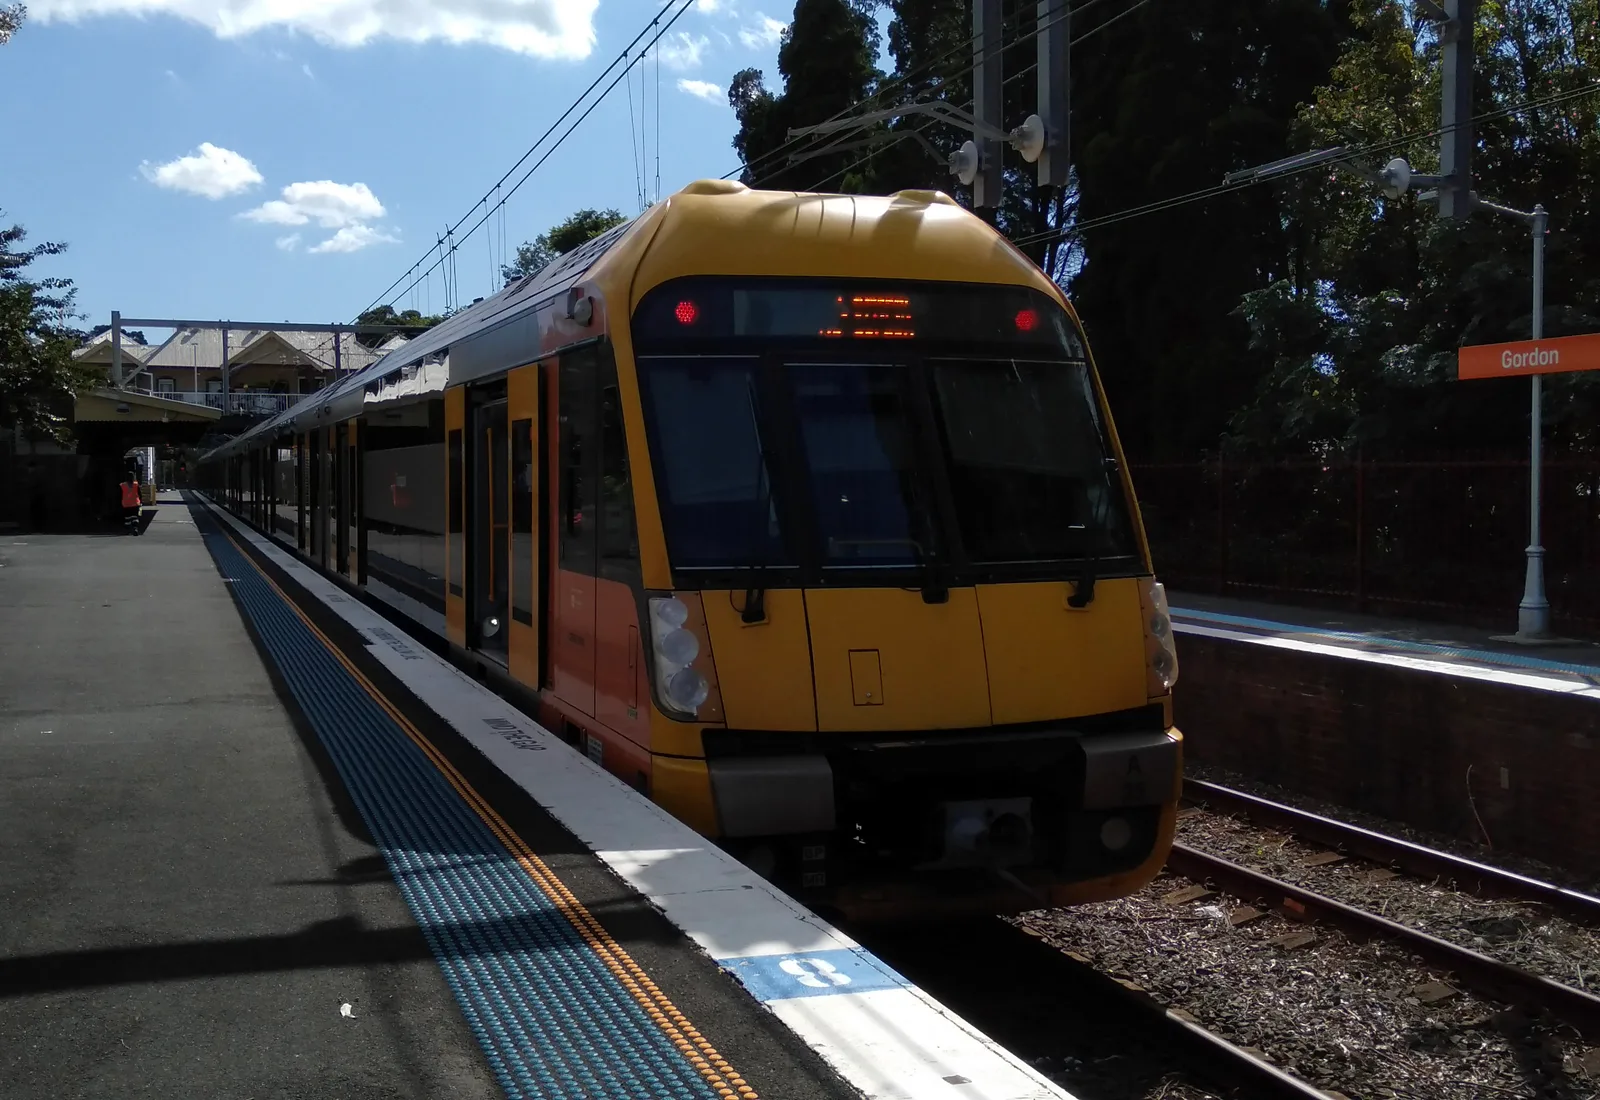
Gordon is the busiest, most cosmopolitan and most rental-heavy of the upper north shore — the de facto town centre that quieter Killara and Pymble lean on. This briefing sets out the catchment and the format that fits.
Gordon is the commercial anchor of its stretch of the upper north shore. The resident base is also distinctive — a median age of 39, an average household of 2.7, 35.3% renting (high for Ku-ring-gai), and a median personal income of $1,075 a week, above the Greater Sydney $881.
What sets Gordon apart from the rest of the line is who lives here. It is the only majority-overseas-born suburb on this stretch (55.8%), with the highest Chinese ancestry (34.5%) and a visible Korean community — Mandarin (20.2%), Cantonese (9.0%) and Korean (5.0%) are all spoken at home, and the apartment stock around the interchange is denser than the surrounding garden suburbs. The food and service demand is therefore real and specific: authentic East-Asian and quality-casual formats banking the interchange flow have a genuine market. Read this briefing, then position to complement the centre rather than fight it head-on.
Gordon's resident numbers describe a cosmopolitan, apartment-dense, rental-heavy town centre rather than the homogeneous garden suburb of its neighbours — a median age of 39, an average household of 2.7, 35.3% renting (high for Ku-ring-gai), and a personal income ($1,075/week) above the Greater Sydney median. The base is the only majority-overseas-born suburb on this stretch (55.8%), with the highest Chinese ancestry on the line (34.5%), a visible Korean community, and Mandarin, Cantonese and Korean all widely spoken at home.
The decisive catchment is the town-centre footfall. The Gordon Centre, the Pacific Highway retail and a major T1 interchange concentrate the wider upper north shore's trade here, and the cosmopolitan base creates a real, specific demand for authentic East-Asian and quality-casual food. The operator implication is a distinctive format that complements the Gordon Centre — priced and positioned for the cosmopolitan, apartment-dense catchment, on the station-to-centre desire-line, doing what the mall food court cannot.
Only majority-overseas-born suburb on this stretch.
Gordon — household income$2,460
vs $2,077 Greater Sydney.
Source: ABS Census 2021 — Gordon (NSW) [1] and Greater Sydney [2]. The Gordon Centre, Pacific Highway retail and T1 interchange (see references) concentrate the wider upper north shore catchment on top of the resident base.
The town-centre anchor the upper north shore leans on
Gordon is the commercial heart of this stretch of Ku-ring-gai. That concentration is the whole point: in a corridor of low-density garden suburbs, Gordon is where the footfall pools, and an operator who banks that pooled flow has a market the surrounding suburbs cannot supply on their own.
For an operator, that makes location relative to the centre and the interchange decisive. A coffee or food format on those lines banks the concentrated flow; one off them, on a quiet residential street, relies on destination visits the town-centre trade rarely makes.
The most cosmopolitan base on the line
Gordon's resident base is unusual for the upper north shore. The 2021 Census records it as the only majority-overseas-born suburb on this stretch (55.8%), with the highest Chinese ancestry of any suburb on the line (34.5%) and a visible Korean community. Mandarin (20.2%), Cantonese (9.0%) and Korean (5.0%) are all spoken at home, and the apartment stock around the interchange is denser and more rental-heavy (35.3% renting) than the garden suburbs around it. This is a cosmopolitan, internationally diverse catchment, not the homogeneous family-suburb profile of Killara or Pymble.
The operator implication is a specific, real food demand. An authentic East-Asian offer — Chinese or Korean, done genuinely well — has a built-in market here that it would not have a few stations away, and a quality-casual format aimed at the cosmopolitan, apartment-dense base reads the catchment correctly.
The interchange concentrates the footfall
Gordon's T1 North Shore rail interchange is the engine that makes it the town centre. It is the busiest station on this stretch of the line, pulling commuters, students and the wider catchment through the precinct daily and concentrating a footfall the residential suburbs around it do not generate. The denser apartment stock that has grown up around the interchange adds a resident base that lives within walking distance of the shops and the platform — a more urban, more transit-oriented pattern than the rest of Ku-ring-gai.
For an operator, the interchange flow is the foundation of the trading week. The commuter pulse — morning coffee on the way to the platform, an after-work pickup on the way home — plus the all-day flow of the catchment moving through the town centre is the productive trade. A grab-and-go coffee or a quality-casual food format positioned on the station-to-centre desire-line banks that flow; one positioned away from it relies on a destination visit.
Format, competition and the rental-heavy base
Gordon's catchment is more rental-heavy and apartment-dense than its neighbours (35.3% renting, average household 2.7), which supports a more urban, more frequent eating-out pattern than a pure owner-occupier garden suburb. The food market reflects that — a real demand for authentic East-Asian and quality-casual dining, layered on the town-centre footfall.
The strategic question is differentiation. Gordon has the footfall, the transit flow and a distinctive, cosmopolitan demand — but the operators who win are the ones who do something the Gordon Centre and the existing strip do not. An authentic Chinese or Korean offer, a specialty café with a genuine point of difference, or a quality-casual format that reads the apartment-dense base will bank the concentrated town-centre trade. A bland, mainstream concept with no edge competes on the centre's terms and struggles. The composite of 63 (VERIFY) reflects exactly this: strong, concentrated demand held below PROCEED by a dominant incumbent and a competitive strip.
The format that fits, in plain terms
A specialty café with a genuine point of difference fits the same catchment (café 65/100), positioned on the commuter and town-centre desire-line. Retail is harder (56/100): the Gordon Centre owns the mainstream mall trade, so a retail entrant needs a specialist niche the centre does not cover.
What does not fit: a bland, mainstream offer that competes directly with the Gordon Centre's tenants on their own ground; a generic convenience format with no point of difference; or a position off the station-and-centre desire-lines, away from where the catchment's concentrated footfall moves.
Zone-by-zone breakdown
Station & interchange
The T1 North Shore rail interchange — the busiest on this stretch, the commuter and catchment pulse. Works for: grab-and-go coffee and quality-casual food on the commuter desire-line. Fails for: leisurely formats off the platform flow relying on destination visits.
Pacific Highway retail strip
The shopfront strip along the highway — the established food-and-service operators. Works for: authentic East-Asian and quality-casual dining the strip lacks. Fails for: me-too concepts duplicating an incumbent already banking the flow.
Operator Intelligence
10 dimensions — what matters most here
Scored 1–10 from an operator perspective: higher always means better. Each dimension includes the reasoning behind the score.
Rail interchange flowCritical
The busiest T1 North Shore station on this stretch concentrates a commuter and catchment footfall the residential suburbs cannot generate.
8/10
Chinese / Korean food demandCritical
The highest Chinese ancestry on the line (34.5%) and a visible Korean community give authentic East-Asian formats a built-in market.
8/10
Apartment-dense rental baseImportant
The most rental-heavy, apartment-dense suburb on the line (35.3% renting) supports a more frequent, urban eating-out pattern.
7/10
Gordon Centre competitionCritical
The enclosed shopping centre owns the mainstream mall trade — the binding constraint that holds the composite at CAUTION.
4/10
When Gordon trades
Peak and off-peak trading periods
Strong
Weekday morning & commute (06:30–10:00)
The T1 interchange commuter pulse plus the town-centre flow — the daily coffee peak.
Moderate
Weekday after-work (16:30–19:00)
The commuter return through the interchange plus apartment residents arriving home.
Operator fit warning
Who should not open in Gordon
✕
Generic convenience formats with no point of difference against the established strip.
✕
Concepts positioned off the station-and-centre desire-lines, away from the concentrated footfall.
Best business formats for Gordon
Specialty coffee on the interchange flow
A busy T1 interchange plus the town-centre footfall feeds a daily commuter and all-day coffee trade. A specialty café with a genuine point of difference on the station-to-centre desire-line banks the concentrated flow (café 65/100).
Quality-casual for the apartment-dense base
The most rental-heavy, apartment-dense suburb on the line (35.3% renting) supports a more frequent eating-out pattern. A quality-casual format aimed at the cosmopolitan base reads the catchment the mainstream mall offer misses.
Risks specific to Gordon
The Pacific Highway strip is competitive
Established food-and-service operators already bank the town-centre flow. A me-too concept duplicating an incumbent has to earn its place against businesses that already hold the footfall.
A bland offer misses the distinctive demand
Gordon's edge is its cosmopolitan, majority-overseas-born base. An operator who treats it as a generic affluent suburb and pitches a bland offer misses the authentic East-Asian and quality-casual demand that actually sets the suburb apart.
Common mistakes
How operators get Gordon wrong
Treating Gordon as a generic affluent suburb
Gordon's edge is its cosmopolitan, majority-overseas-born base and its authentic East-Asian demand. A bland offer pitched at an imagined homogeneous garden suburb misses the distinctive market that actually sets Gordon apart from Killara and Pymble.
Underrated signals
Hidden advantages in Gordon
The catchment Killara and Pymble lean on
As the de facto town centre, Gordon banks not only its own residents but the wider upper north shore catchment that comes here for shops, services and the station — a footfall the quieter neighbouring suburbs cannot supply on their own.
A built-in authentic-food market
The highest Chinese ancestry on the line (34.5%), a visible Korean community and a majority-overseas-born base give a genuine East-Asian offer a demand it would not have a few stations away — a market the Gordon Centre's food court does not satisfy.
A transit-oriented, apartment-dense base
The denser apartment stock and rental-heavy profile (35.3% renting) around the interchange give Gordon a more urban, more frequent eating-out pattern than the owner-occupier garden suburbs around it.
Rent viability bands for Gordon
Only figures that remain after the unsupported-claim check are shown. A blank table means this page is not quoting rent.
Census baseline: ABS Census 2021 (suburb / SAL), with Greater Sydney benchmarksValidate against the exact lease before signing
Band
Range
What it buys
Works for
Fails for
Pacific Highway strip
Indicative — mid-to-high tier
A shopfront on the established highway retail strip off the prime core.
Authentic East-Asian and quality-casual dining the strip lacks.
Me-too concepts duplicating an incumbent already banking the flow.
Secondary / off the desire-line
Indicative — lower tier
A position away from the station-and-centre footfall.
Destination formats with a genuine pull that do not need passing trade.
Coffee and convenience formats relying on a footfall that does not reach the position.
Both are cosmopolitan, transit-anchored North Shore centres with strong East-Asian food demand, but Chatswood is a far larger major centre — a metro-and-rail interchange, two malls and a deep dining scene — while Gordon is a smaller town-centre anchor for the quieter upper north shore. Chatswood has more scale and footfall; Gordon has less competition density and a town-centre role the surrounding suburbs depend on.
Decision framework
Are you positioned on the station-to-centre desire-line where the interchange and town-centre footfall actually moves?
Does your concept read Gordon's distinctive base — majority overseas-born, highest Chinese ancestry on the line, a visible Korean community — rather than treating it as a generic affluent suburb?
Can your model bank the apartment-dense, rental-heavy eating-out pattern rather than relying on a thin owner-occupier village trade?
Gordon offers the concentrated footfall of the upper north shore's town-centre-and-interchange anchor — but only for a distinctive format that complements the Gordon Centre rather than fighting it. Locatalyze runs an address-level analysis on the exact tenancy: the real foot traffic on the station-to-centre line, the competing restaurant-and-café set against the Gordon Centre and the Pacific Highway strip, indicative upper north shore rent against your format, and a break-even built on the interchange and town-centre flow rather than thin residential trade. Before you sign in Gordon, get the town-centre catchment and competition read right.
Gordon insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
More questions about opening in Gordon
What rent should I expect in Gordon?
Premium upper north shore town-centre levels on the prime station-and-centre line, easing on the Pacific Highway strip and secondary positions. The bands here are indicative envelopes — verify commercial comps for the specific tenancy. The footfall is concentrated, so a prime frontage on the desire-line is the dearest and the secondary positions off it cheaper but reliant on a destination pull.
Who is the Gordon customer?
A cosmopolitan, apartment-dense, rental-heavy town-centre catchment: 8,795 residents, median age 39, the only majority-overseas-born suburb on the line (55.8%), the highest Chinese ancestry (34.5%) and a visible Korean community (Mandarin 20.2%, Cantonese 9.0%, Korean 5.0% spoken at home), plus the wider Killara and Pymble catchment and the interchange commuter flow. Personal income $1,075/week, above the Greater Sydney $881.
Is the Korean and Chinese food demand real?
Yes — it is the suburb's distinctive edge. Gordon has the highest Chinese ancestry on the line (34.5%), a visible Korean community (~5%), and Mandarin (20.2%), Cantonese (9.0%) and Korean (5.0%) all spoken at home, on a majority-overseas-born base (55.8%). An authentic Chinese or Korean offer done genuinely well has a built-in market here that it would not have a few stations away — provided it out-executes the food court rather than duplicating it.
Data provenance & limitations. Demographic figures are from the ABS 2021 Census for the Gordon (NSW) suburb (SAL11724), with Greater Sydney (1GSYD) as benchmark; the 2021 Census is the most recent available. Owner-occupied is the sum of owned outright (32.3%) and owned with a mortgage (30.6%). The Gordon Centre, Pacific Highway retail and T1 North Shore rail interchange descriptions are from Wikipedia and Transport for NSW, secondary links to primary reporting; specific tenancy and patronage counts are not asserted here. Rent bands are indicative envelopes, not achieved rents — informed by Gordon's premium upper north shore town-centre positioning; verify commercial comps for the specific tenancy. Factor scores are relative estimates calibrated across all Locatalyze suburbs, not guarantees of outcome.
Methodology: Scores are engine-derived from five observable inputs (demand strength, rent pressure, competition density, seasonality risk, tourism dependency — each 1–10). These feed into business-type-specific weighted composites via a single scoring engine used across all markets. Scores are relative estimates calibrated across all Sydney suburbs — a score of 80 indicates materially better conditions than 65; it is not a success probability or guarantee.
Frequently Asked Decision Questions
Have a specific address in Gordon?
Run a free location check — named competitors, a rent benchmark, and location score, data confidence, and proceed / verify / avoid recommendation — for any Gordon address.
Gordon insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
·4.3★ and 626 reviews — customers actively recommend this café.
·Review volume 55% above peer average (405).
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
If you are opening nearby: The Wyatt is the benchmark café here — their 4.3★ and 626 reviews beat the 405-review peer average — $$ positioning is validated by review depth in this catchment — 311m from centre — frontage on the walkable strip matters.
·4.4★ and 521 reviews — customers actively recommend this café.
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
·Central location (200m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: Pure Brew & Co. Gordon (Dominant) shows what execution looks like at this score tier — their 4.4★ and 521 reviews beat the 416-review peer average — $$ positioning is validated by review depth in this catchment — 200m from centre — frontage on the walkable strip matters.
·4.3★ and 539 reviews — customers actively recommend this café.
·Review volume 30% above peer average (414).
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
If you are opening nearby: Pottery Green Bakers Gordon (Dominant) shows what execution looks like at this score tier — their 4.3★ and 539 reviews beat the 414-review peer average — $$ positioning is validated by review depth in this catchment — 218m from centre — frontage on the walkable strip matters.
4. Missing Spoon (Gordon)
★★★★☆ 4.4 (390 reviews) · $$ · 217m from centre
73 · Established
·4.4★ and 390 reviews — customers actively recommend this café.
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
·Central location (217m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: 4.4★ with 390 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment — 217m from centre — frontage on the walkable strip matters.
5. McDonald's Gordon
★★★½☆ 3.6 (1,253 reviews) · $ · 100m from centre
60 · Growing
·1,253 reviews place it on the local shortlist even where ratings are mixed.
·Rating sits below the 4.5★ peer average — volume or convenience may be doing the work.
·Review volume 274% above peer average (335).
If you are opening nearby: $ positioning is validated by review depth in this catchment — 100m from centre — frontage on the walkable strip matters — For new entrants: McDonald's Gordon is beatable on pastry-forward with a limited hot menu — avoid matching incumbents' full menu breadth.
Who wins in Gordon — Restaurants
Ranked by success score (rating, review depth, centrality) within ~1000m of the suburb centre.
What winners have in common
·8 of 10 top venues sit at 4.3★+ — customers reward consistent execution, not novelty alone.
·Review depth averages 515 — operators with under 150 reviews read as unproven next to incumbents.
·Typical positioning is $$ (8 venues report Google price tiers).
·6 benchmark operators combine 4.4★+ ratings with 150+ reviews — new entrants need a clear niche, not a me-too menu.
·4.4★ and 654 reviews — customers actively recommend this restaurant.
·Review volume 31% above peer average (500).
·Value-tier pricing with high volume — wins on convenience and price, not premium experience.
If you are opening nearby: Subway® Restaurant is the benchmark restaurant here — their 4.4★ and 654 reviews beat the 500-review peer average — $ positioning is validated by review depth in this catchment — 97m from centre — frontage on the walkable strip matters.
·4.5★ with 536 reviews — repeat local demand, not one-off visits.
·Value-tier pricing with high volume — wins on convenience and price, not premium experience.
·Central location (177m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: Curry Monitor (Dominant) shows what execution looks like at this score tier — 4.5★ with 536 reviews signals repeat custom, not novelty traffic — $ positioning is validated by review depth in this catchment — 177m from centre — frontage on the walkable strip matters.
·4.2★ and 727 reviews — customers actively recommend this restaurant.
·Rating sits below the 4.4★ peer average — volume or convenience may be doing the work.
·Review volume 48% above peer average (492).
If you are opening nearby: Thai Riffic Gordon (Dominant) shows what execution looks like at this score tier — 4.2★ with 727 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment — 81m from centre — frontage on the walkable strip matters.
4. AMAZONA Premium Acai & Dessert Gordon
★★★★½ 4.9 (257 reviews) · 33m from centre
86 · Dominant
·4.9★ with 257 reviews — repeat local demand, not one-off visits.
·0.5★ above the 4.4★ average among top local peers.
·Central location (33m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: AMAZONA Premium Acai & Dessert Gordon (Dominant) shows what execution looks like at this score tier — 4.9★ with 257 reviews signals repeat custom, not novelty traffic — 33m from centre — frontage on the walkable strip matters.
·4.3★ and 539 reviews — customers actively recommend this restaurant.
·Mid-range positioning with strong review depth — balanced offer, not discount-led.
·Central location (218m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: Pottery Green Bakers Gordon (Dominant) shows what execution looks like at this score tier — 4.3★ with 539 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment — 218m from centre — frontage on the walkable strip matters.
Who wins in Gordon — Retail
Ranked by success score (rating, review depth, centrality) within ~1500m of the suburb centre.
What winners have in common
·4 of 10 top venues sit at 4.3★+ — customers reward consistent execution, not novelty alone.
·No single venue dominates on both rating and review depth — the category may still be contestable.
·Most winners sit within 400m of the suburb centre — frontage on the walkable strip matters.
1. Curvy - Bra Fittings
★★★★½ 4.9 (76 reviews) · 831m from centre
75 · Established
·4.9★ rating beats the typical retail baseline in this catchment.
·0.5★ above the 4.4★ average among top local peers.
·Review volume 695% above peer average (10).
If you are opening nearby: their 4.9★ and 76 reviews beat the 10-review peer average — For new entrants: A service-heavy or experiential retail concept can win where product-only formats like Curvy look interchangeable.
2. Aqua Shop Sydney
★★★★½ 4.7 (44 reviews) · 183m from centre
68 · Established
·4.7★ rating beats the typical retail baseline in this catchment.
·0.3★ above the 4.4★ average among top local peers.
·Review volume 236% above peer average (13).
If you are opening nearby: their 4.7★ and 44 reviews beat the 13-review peer average — 183m from centre — frontage on the walkable strip matters — For new entrants: A service-heavy or experiential retail concept can win where product-only formats like Aqua Shop Sydney look interchangeable.
3. Tailor & Trim
★★★★½ 4.7 (13 reviews) · 1365m from centre
54 · Growing
·4.7★ rating beats the typical retail baseline in this catchment.
·0.3★ above the 4.4★ average among top local peers.
If you are opening nearby: For new entrants: A service-heavy or experiential retail concept can win where product-only formats like Tailor & Trim look interchangeable.
4. Vinnies Gordon
★★★½☆ 3.7 (25 reviews) · 143m from centre
40 · Emerging
·Rating sits below the 4.6★ peer average — volume or convenience may be doing the work.
·Review volume 64% above peer average (15).
·Central location (143m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: 143m from centre — frontage on the walkable strip matters — For new entrants: A service-heavy or experiential retail concept can win where product-only formats like Vinnies Gordon look interchangeable.
5. Rodney Clark - Gordon
★★★½☆ 3.7 (3 reviews) · 57m from centre
34 · Emerging
·Rating sits below the 4.6★ peer average — volume or convenience may be doing the work.
·Central location (57m from suburb centre) captures pass-by and destination traffic.
If you are opening nearby: 57m from centre — frontage on the walkable strip matters — For new entrants: A service-heavy or experiential retail concept can win where product-only formats like Rodney Clark look interchangeable.