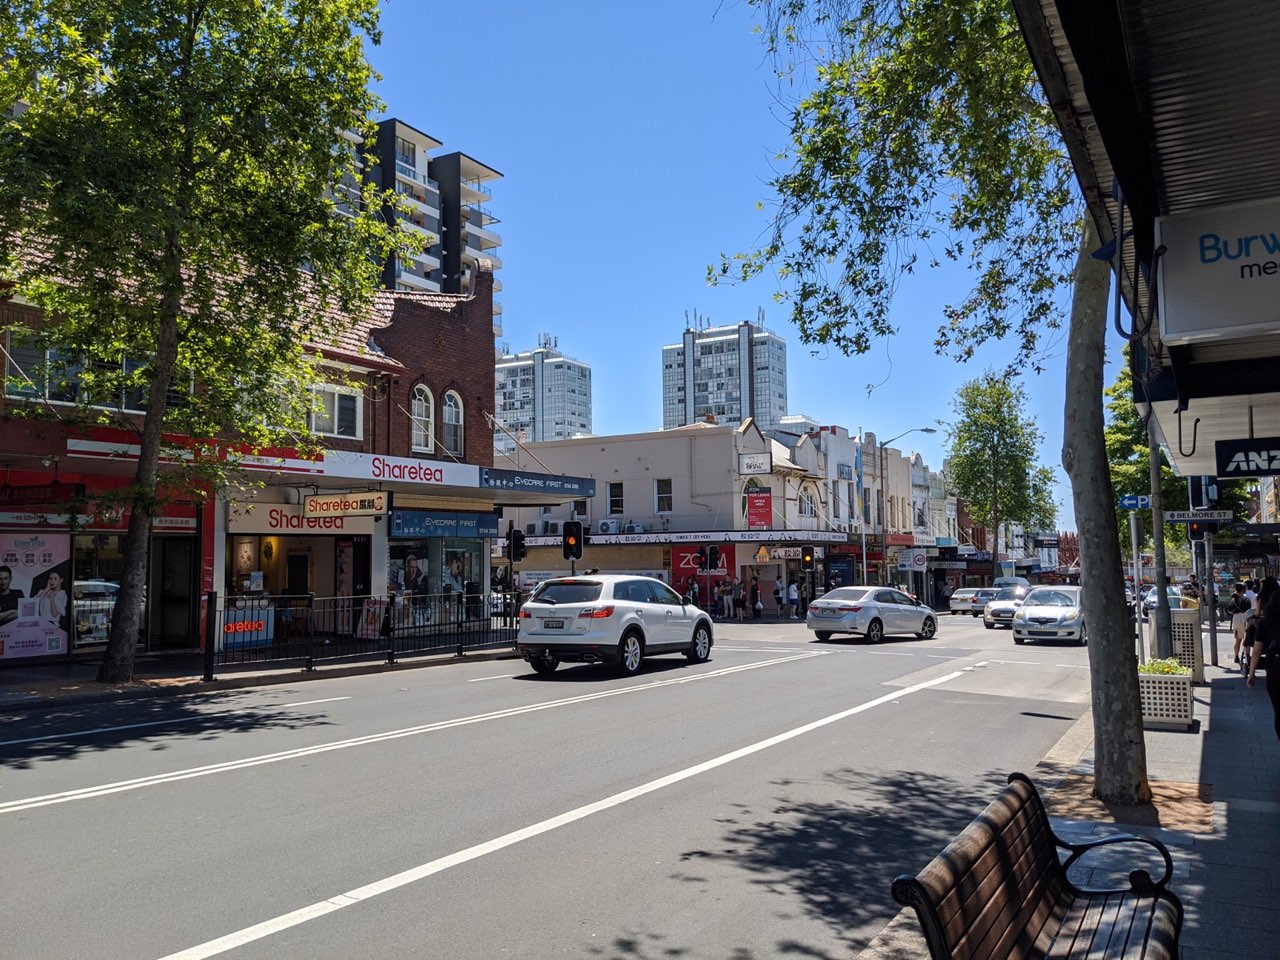
If you are considering a café in Burwood
Pick position before menu.
Decision: position-matched specialty with weekday-baseline staffing — or walk away from peak-night rent signed after one Friday walk.

Sydney Suburb Intelligence
Burwood scores 68/100 — VERIFY.
Burwood insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
Location score
Recommendation
VERIFY
Potentially viable — important checks remain
30 businesses sampled near Burwood centre (last refreshed 27 June 2026); suburb scores use Locatalyze engine v7.4.0. Suburb-centre snapshots for Burwood — validate at your lease address before signing.
Café 69, restaurant 67 and retail 66 sit within 3 points. The model is not choosing a format. The suburb verdict is VERIFY at 68/100.
No factor is in a tight band. Demand is 8/10, rent pressure 5/10, competition 6/10, and seasonality 3/10. The verdict comes from the weighted blend, not from one red flag.
A competitor snapshot lists 30 venues. That is an observation from the snapshot, not evidence the suburb is under-supplied.
This is a reading of the five factors and three format scores on this page. It is not a rent quote, a competitor count, or a reason to sign a lease.
How to read these scores
Composite 68/100. The format scores sit within 3 points, so this panel does not pick a format.
Source
Locatalyze engine v7.4.0 plus cached local competitor evidence
Freshness
Competitor cache refreshed 27 June 2026
Confidence
Medium - 30 businesses sampled
Limitation
Burwood scores screen the suburb, not the lease. The paid report tests frontage, rent, nearest competitors, and break-even at your exact address.
Evidence freshness
Scores
Engine v7.4.0; suburb-level model
Competition
Google Places cache refreshed 27 June 2026
Rent
No sourced asking-rent series — obtain current listings
Demographics
ABS Census 2021 is cited only where this page states a count. A score is not a census figure.
Factor Breakdown
Demand, rent, competition, seasonality, and tourism — scored and weighted for Australian commercial operators.
Business-Type Scores
Scores use engine-derived weights: cafés weight demand and rent most heavily; restaurants factor tourism; retail factors tourism and demand equally.
Analyst Notes — Burwood
Demand 8/10: Burwood Road Korean and Asian restaurant corridor draws destination diners from across inner-west and north-west Sydney.
Tourism 6/10: significant Korean diaspora visitor spend makes this a genuine dining destination rather than a local-only market.
Decision tree
Burwood Road is Sydney's most established Korean-and-Asian restaurant destination strip — 9,000–14,000 weekday pedestrians, rail access pulling diners from inner-west and north-west, and demand that reads genuinely strong. Composite location score is 68/100 with a VERIFY verdict for cafés at 69/100 — not because the catchment is weak, but because the core strip carries 60–80 hospitality operators in 400 metres and Fri–Sat evening can deliver 55–65% of weekly revenue for destination formats while weekday lunch runs at half-to-two-thirds that rate. Ice Kirin Bar Burwood (4.6★, 700 reviews), De Vu Café, WOW! Food, and Charlie's On George already hold recommendation paths. The trap is signing core-strip prime rent after one Friday night walk, assuming Burwood is Korean-cuisine-only, or treating Westfield as an extension of the strip.
Core-strip density and weekend-weighted revenue are the binding constraints — zone and daypart before concept.
The competitor snapshot surfaces Ice Kirin Bar Burwood (700 reviews), De Vu Café Burwood (486 reviews), WOW! Food (5.0★), and Charlie's On George Cafe within the core trade area. Your concept must answer whether it pulls destination visitors and local-resident repeat, or which daypart wedge it owns — not whether Burwood looks busy on a Saturday evening alone.
Pick position before menu.
Decision: position-matched specialty with weekday-baseline staffing — or walk away from peak-night rent signed after one Friday walk.
Generic Korean BBQ or hotpot faces 25–35 established competitors within 400 metres.
Quality non-Asian formats with clear identity — Italian, Middle Eastern, modern Australian — pull local residents and inner-west visitors seeking variety. Category choice matters less than product depth and concept identity.
Capacity and staffing calibrated to weekday baseline with flexible weekend ramp — Fri–Sun 55–65% of weekly revenue for destination-led formats; rent evaluated against weighted-average revenue, not peak night alone.
Decision: differentiated concept serving both destination visitors and local-resident repeat — or walk away from category-only competition on saturated core strip.
Density is high but consumer demand for the format is also high — new entrants need strong product, not category presence alone.
Decision: late-evening daypart wedge with product identity — not daytime-only format on destination-strip rent.
Strathfield carries denser Korean-and-Japanese clustering with stronger weekday office-and-student lunch. Burwood carries stronger weekend destination-visitor flow and wider non-Asian customer mix — format choice depends on weekday versus weekend revenue weighting.
Ashfield has stronger Chinese-cuisine clustering with deeper community roots. Burwood has stronger pan-Asian destination identity and better rail access to north-west catchment.
Operators who import Strathfield weekday-lunch assumptions to Burwood core-strip rent over-capitalise for weekend peaks and cash-stress Tue–Thu.
Burwood is not Korean-cuisine-exclusive — quality non-Asian formats with identity perform. It is also not open to generic category entries — 60–80 operators across cuisines inside 400 metres punish undifferentiated concepts.
Walk the strip twice: weekday afternoon and weekend evening. Visible Monday lunch density is meaningfully less than Friday night operating pressure.
Destination visitors are price-tolerant and event-driven; local residents are frequency-sensitive and reliability-driven. Fit-for-both formats perform strongest.
Decision: honest competitive count and dual-customer modelling before LOI — not headline catchment enthusiasm alone.
Invest if your format is differentiated inside a dense cluster or distinctly identified outside it — with weekday-baseline cost structure.
Invest if position matches rhythm: northern stretch for residential café, side-streets for weekday services, core strip for destination concepts with weekend ramp discipline.
Walk away if you are generic Korean BBQ or hotpot without regional depth or signature program.
Walk away if you sign core-strip prime rent calibrated to Friday–Saturday peak observation only.
Walk away if you treat Westfield Burwood and the strip as one market.
Which precinct — core strip prime, core secondary, northern stretch, side-streets, or Westfield mall (separate decision).
Burwood Road core at 12:30pm Tuesday and 7:30pm Friday — count direct and adjacent competitors within 400m at each time.
Burwood station at 8:15am if your model needs commuter grab-and-go versus residential weekday loyalty.
Nearest named competitors within 200m — Ice Kirin Bar, De Vu Café, WOW! Food, or Charlie's On George.
Rent at quoted $/m² clearing on weighted-average weekly revenue — not Fri–Sat extrapolation alone.
400 metres between station and Westfield — highest density, destination-visitor capture, sharpest weekend-versus-weekday split. Best for differentiated Asian cuisine, quality non-Asian with identity, late-evening specialty.
Toward Five Dock and Concord — residential-anchored rhythm, softer destination flow. Best for local-anchored cafés, neighbourhood independents, allied health.
Side-streets with allied services and weekday-stable rhythm — minimal destination flow. Best for allied health, specialty retail, weekday-anchored cafés.
Separate sub-market — mall-anchored flow, brand-led tenancy mix, own rent mechanics. Best for brand retail, mall-calibrated casual dining — not strip-identity destination concepts.
Operator Intelligence
Scored 1–10 from an operator perspective: higher always means better. Each dimension includes the reasoning behind the score.
Core strip 9,000–14,000 weekday pedestrians; Fri–Sat evening intensity well above baseline. Rail connectivity expands catchment.
Destination-diner demand is real but weekend-loaded — weekday baseline materially softer for destination-led formats.
Westfield and strip support specialty and culturally-aligned retail — generic categories struggle against mall and online.
Dual profile — destination visitors price-tolerant; local residents value-conscious. Plan against both.
Local residents form strong repeat with consistent quality; fit-for-both formats earn strongest combined base.
60–80 operators in 400m — generic entries face established incumbents; differentiated entries have clearer path.
Burwood station — direct rail from CBD, inner-west, and north-west; drives destination catchment range.
Minimal international tourism — Korean diaspora visitor layer is niche; domestic destination-diner model.
Mature precinct with Liverpool Road residential densification — differentiation still finds runway; undifferentiated entries saturated.
When Burwood trades
Friday–Saturday evening (6pm–11pm)
Dominant peak — destination diners from inner-west and north-west; highest weekly volume across these evenings.
Sunday lunch and afternoon
Family-group and local-resident dining — secondary weekend peak for yum-cha-adjacent formats.
Weekday lunch (Mon–Thu)
Office workers, residents, station commuters — model at half-to-two-thirds weekend-evening rate.
Late evening (10pm–midnight, Fri–Sat)
Dessert, bubble tea, specialty beverage cross-flow from dining trade — stronger than most inner-west strips.
Operator fit warning
Generic Korean BBQ or hotpot without product or positioning differentiation against 25–35 established competitors within 400 metres.
Operators planning cost structure against Friday–Saturday peak without weekday-baseline modelling.
Single-customer-type concepts — destination-only or local-only without fit-for-both discipline.
60–80 hospitality operators inside 400 metres — new entrants without differentiation lose volume against multi-year incumbents.
Fri–Sun 55–65% of weekly revenue for destination restaurants — rent and staffing against peak night drains operating envelope Mon–Thu.
Assuming Korean-only territory excludes viable non-Asian formats, or that category presence alone clears margin in saturated cluster — both fail.
Mall and strip operate on different customer flows and tenancy mechanics — format-position misalignment when treated as one market.
Common mistakes
Friday–Saturday evening commits to peak-calibrated cost structure — weekday base at half-to-two-thirds drains operating envelope across majority of trading days.
Quality non-Asian formats with identity perform; generic non-Asian without concept identity do not — binary thinking fails both directions.
Different customer flows, tenancy mechanics, and rhythms — assumptions from one applied to the other produce format misalignment.
Underrated signals
Direct connectivity pulls diners from Hills District, north-west, and inner CBD corridor — geographic range few inner-west strips match without train line.
21:00–23:00 window structurally stronger than Marrickville or Ashfield — dessert and specialty beverage formats capture meal-completion flow.
Only figures that remain after the unsupported-claim check are shown. A blank table means this page is not quoting rent.
| Band | Range | What it buys | Works for | Fails for |
|---|---|---|---|---|
| Westfield Burwood mall | Tenancy-specific — direct landlord engagement | Mall-anchored flow, brand-led tenancy mix | Brand retail, mall-calibrated casual dining, allied services with visibility | Strip-identity destination concepts, low-volume independents without mall throughput |
Suburb comparison
Ashfield: stronger Chinese clustering and community roots. Burwood: stronger Korean-and-pan-Asian destination identity and north-west rail access. Burwood wins for pan-Asian destination; Ashfield for Chinese specialty.
Strathfield: denser Korean-Japanese cluster, stronger weekday lunch. Burwood: stronger weekend destination flow, wider non-Asian mix. Choose by weekday versus weekend revenue weighting.
Burwood rewards operators who plan against density, weekend-weekday split, and monoculture misread — differentiation and weekday-baseline cost structure before strip glamour.
Fit-for-both formats earning destination visitors and local-resident repeat perform strongest; peak-night rent without Tue–Thu revenue honesty fails.
Related Sydney reading
Burwood suburb-level scoring captures dense destination demand but not whether the tenancy sits in saturated core-strip density, residential northern stretch, side-street allied rhythm, or Westfield mall. Locatalyze runs address-level analysis surfacing competitive set, customer profile, and revenue envelope at the specific position.
Burwood insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
Yes, with clear identity and quality positioning. Local residents and inner-west visitors seeking variety support differentiated non-Asian formats. Generic formats without concept identity struggle.
Generic Korean BBQ, hotpot, and fried chicken are effectively saturated. Differentiated regional depth or signature programs still find room. Category presence alone does not clear margin.
Destination-led core-strip restaurants: 55–65% Fri–Sun, weekday at half-to-two-thirds weekend-evening rate. Northern-stretch cafés: more balanced weekday anchor. Calibrate staffing and rent to weighted average.
Strathfield: stronger weekday office-and-student lunch, denser Korean-Japanese cluster. Burwood: stronger weekend destination flow, wider non-Asian mix, better north-west rail catchment. Choose by revenue weighting.
Methodology: Scores are engine-derived from five observable inputs (demand strength, rent pressure, competition density, seasonality risk, tourism dependency — each 1–10). These feed into business-type-specific weighted composites via a single scoring engine used across all markets. Scores are relative estimates calibrated across all Sydney suburbs — a score of 80 indicates materially better conditions than 65; it is not a success probability or guarantee.
Run a free location check — named competitors, a rent benchmark, and location score, data confidence, and proceed / verify / avoid recommendation — for any Burwood address.
Burwood insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
Demand 10/10: King Street delivers unmatched independent hospitality foot traffic with a loyal, high-frequency local demographic.
Demand 10/10: Crown Street is one of Australia's densest premium hospitality strips — 400+ venues drawing high-income professional residents.
PROCEED at composite 73: demand 10/10 and seasonality 2/10 clear the ≥69 threshold. Rent 6 and competition 6 are the costs of that demand — the same rent factor as Surry Hills, not a discount.
Local competition
Ranked from cached Google Places data near the suburb centre. Validate at your lease address before signing.
Ranked by success score (rating, review depth, centrality) within ~800m of the suburb centre.
What winners have in common
★★★★½ 4.6 (700 reviews) · $$ · 109m from centre
If you are opening nearby: Ice Kirin Bar Burwood is the benchmark café here — their 4.6★ and 700 reviews beat the 470-review peer average — $$ positioning is validated by review depth in this catchment — 109m from centre — frontage on the walkable strip matters.
★★★★☆ 4.0 (1,463 reviews) · 469m from centre
If you are opening nearby: For new entrants: Club Burwood RSL's volume comes from breadth — narrow to one daypart (early breakfast or late specialty coffee) rather than their full menu.
★★★★☆ 4.3 (486 reviews) · $ · 175m from centre
If you are opening nearby: 4.3★ with 486 reviews signals repeat custom, not novelty traffic — $ positioning is validated by review depth in this catchment — 175m from centre — frontage on the walkable strip matters.
4. WOW! Food
★★★★★ 5.0 (203 reviews) · 412m from centre
If you are opening nearby: WOW! Food (Dominant) shows what execution looks like at this score tier — 5.0★ with 203 reviews signals repeat custom, not novelty traffic — For new entrants: WOW! Food is beatable on single-origin filter led — avoid matching incumbents' full menu breadth.
5. Oliver Brown Burwood Westfield
★★★½☆ 3.9 (428 reviews) · $$ · 271m from centre
If you are opening nearby: $$ positioning is validated by review depth in this catchment — 271m from centre — frontage on the walkable strip matters — For new entrants: Oliver Brown Burwood Westfield is beatable on pastry-forward with a limited hot menu — avoid matching incumbents' full menu breadth.
Ranked by success score (rating, review depth, centrality) within ~1000m of the suburb centre.
What winners have in common
★★★★☆ 4.3 (1,503 reviews) · $$ · 293m from centre
If you are opening nearby: Sahara By The Park is the benchmark restaurant here — their 4.3★ and 1,503 reviews beat the 891-review peer average — $$ positioning is validated by review depth in this catchment — 293m from centre — frontage on the walkable strip matters.
★★★★☆ 4.0 (1,738 reviews) · $$ · 239m from centre
If you are opening nearby: $$ positioning is validated by review depth in this catchment — 239m from centre — frontage on the walkable strip matters — For new entrants: Before venues like Mr Stonebowl Burwood thicken the cluster, a quality-led casual format with clear dietary options could set a new benchmark.
★★★★☆ 4.0 (1,463 reviews) · 469m from centre
If you are opening nearby: For new entrants: Before venues like Club Burwood RSL thicken the cluster, a quality-led casual format with clear dietary options could set a new benchmark.
4. Sydney Dumpling King Burwood
★★★★☆ 4.2 (814 reviews) · $ · 296m from centre
If you are opening nearby: 4.2★ with 814 reviews signals repeat custom, not novelty traffic — $ positioning is validated by review depth in this catchment — 296m from centre — frontage on the walkable strip matters.
5. Strathfield Sports Club
★★★★☆ 4.1 (915 reviews) · $$ · 871m from centre
If you are opening nearby: $$ positioning is validated by review depth in this catchment — For new entrants: Before venues like Strathfield Sports Club thicken the cluster, a quality-led casual format with clear dietary options could set a new benchmark.
Derived from venue counts and formats in our Google Places snapshot — not a guarantee of demand at your exact address.
Reason: No clear 4.5★+ destination restaurant in local results — evening trade may be underserved.
Reason: Tourism dependency is elevated — visitors want authentic local food without fine-dining price tags.
Ranked by success score (rating, review depth, centrality) within ~1500m of the suburb centre.
What winners have in common
★★★★☆ 4.0 (2,126 reviews) · $ · 392m from centre
If you are opening nearby: Kmart Burwood NSW is the benchmark retail here — $ positioning is validated by review depth in this catchment — 392m from centre — frontage on the walkable strip matters.
★★★★☆ 4.0 (885 reviews) · $$ · 392m from centre
If you are opening nearby: $$ positioning is validated by review depth in this catchment — 392m from centre — frontage on the walkable strip matters — For new entrants: A service-heavy or experiential retail concept can win where product-only formats like Target Burwood look interchangeable.
3. Jay Jays Burwood
★★★★☆ 4.2 (87 reviews) · 280m from centre
If you are opening nearby: 4.2★ with 87 reviews signals repeat custom, not novelty traffic — 280m from centre — frontage on the walkable strip matters — For new entrants: A service-heavy or experiential retail concept can win where product-only formats like Jay Jays Burwood look interchangeable.
4. Just Jeans Burwood
★★★★☆ 4.3 (66 reviews) · 320m from centre
If you are opening nearby: 320m from centre — frontage on the walkable strip matters — For new entrants: A service-heavy or experiential retail concept can win where product-only formats like Just Jeans Burwood look interchangeable.
5. Dotti Burwood
★★★★☆ 4.1 (79 reviews) · 275m from centre
If you are opening nearby: 275m from centre — frontage on the walkable strip matters — For new entrants: A service-heavy or experiential retail concept can win where product-only formats like Dotti Burwood look interchangeable.