
If you are considering a café in Fremantle
Pick economy before menu.
Decision: local-resident café on Market/High or South Fremantle — or South Terrace only with winter P&L clearing rent on locals alone. Walk away from December-visit rent decisions.
Perth Suburb Intelligence
Fremantle scores 66/100 — VERIFY.
Fremantle insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
Comparing suburbs first? Perth analyse hub
Fremantle · Score 66/100 · VERIFY
30 businesses sampled near Fremantle centre (last refreshed 27 June 2026); suburb scores use Locatalyze engine v7.4.0. Suburb-centre snapshots for Fremantle — validate at your lease address before signing.
Decision tree
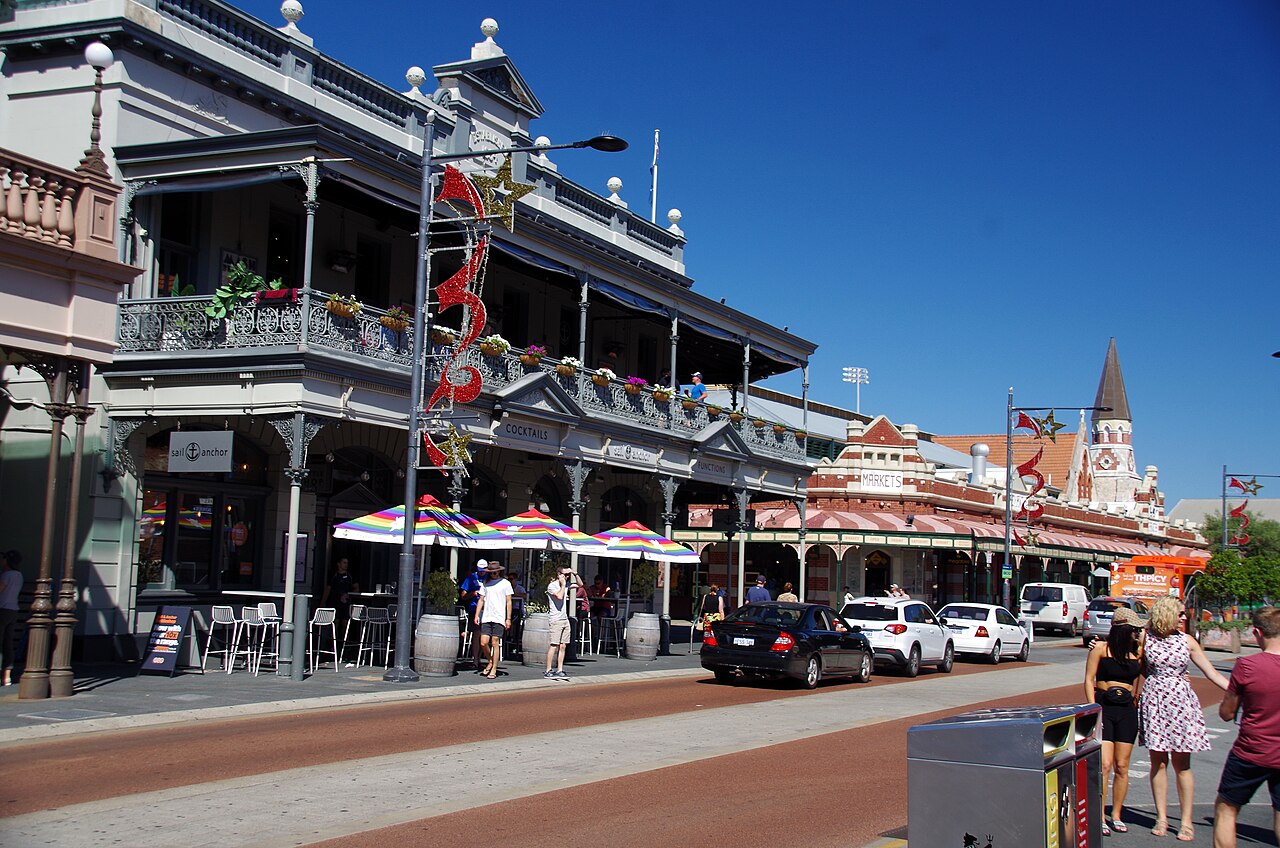
Fremantle runs on two customer economies that do not behave the same — a tourist-driven economy peaking October–April with Fringe World spikes, and a permanent local-resident economy present year-round on Market Street, High Street, and South Fremantle. Demand scores 7/10; rent pressure 6/10; competition 6/10; tourism 8/10. Composite location score is 66/100 with a VERIFY verdict for cafés at 65/100 — not because opportunity is absent, but because South Terrace rent is priced for combined peak demand while winter trade runs on locals alone. Dolce Venezia, For The Record Coffee House, Coccolicco, The Old Synagogue, and Cafe on Hampton already own recommendation paths. The trap is signing Cappuccino Strip rent after a December Saturday visit, or opening a generic format the local-resident base rejects before winter exposes the gap.
Treating tourist browse as sustainable margin at peak rent is the dominant failure mode.
The competitor snapshot surfaces Dolce Venezia (4.9★, 513 reviews), For The Record Coffee House (5.0★, 427 reviews), Coccolicco, The Old Synagogue (731 reviews), Cafe on Hampton, and Palace Patisserie within the core trade area. Your model must break even on local-resident revenue alone — tourist contribution is upside, not baseline.
Pick economy before menu.
Decision: local-resident café on Market/High or South Fremantle — or South Terrace only with winter P&L clearing rent on locals alone. Walk away from December-visit rent decisions.
Evening dining on South Terrace works when local-resident regulars carry winter Thursday–Saturday — tourist summer supplements margin, not baseline. Heritage fit-out constraints add 8–15% effective cost — amortise into lease term.
Waterfront and Fishing Boat Harbour suit seafood-led concepts with seasonal roster discipline — licence or percentage-revenue structures may align better than fixed South Terrace leases.
Decision: neighbourhood restaurant on Market/High with Fremantle identity — or South Terrace with working capital for winter trough. Not generic concept expecting tourist volume year-round.
South Terrace late-trading competes in a dense licensed cluster — local-resident evening base carries winter; tourist spikes lift summer weekends only.
Heritage and noise constraints cap achievable hours on some blocks — model revenue without midnight upside if complaints history exists.
CBD and South Fremantle suit wine bar and neighbourhood formats with lower rent and resident-led mid-week trade.
Decision: neighbourhood bar on Market/High — or South Terrace with explicit summer-banking and winter-floor discipline.
Destination editorial retail with Fremantle identity — vinyl, independent makers, heritage craft — works when product drives deliberate visits, not tourist browse conversion alone.
South Terrace retail faces acute seasonal volatility — local residents do not shop the Cappuccino Strip in winter the way summer tourists browse.
Allied health and appointment services on South Fremantle and CBD blocks absorb resident catchment without tourist-season dependency.
Decision: destination retail with brand pull on Market/High — or allied services on residential strips. Not walk-in retail on South Terrace expecting year-round conversion.
South Terrace rent reflects October–April combined tourist-and-local peak — July weekday volume can run 35–40% of December Saturday. Market/High and South Fremantle trade lower peak at rents sized for local-resident year-round rhythm.
The break-even test: model revenue with zero tourist contribution. If the model fails, you are structurally dependent on seasonal flow you do not control — bank summer surplus explicitly or choose a lower-rent block.
Fremantle identity alignment is prerequisite for local-resident loyalty — formats that read generic lose the stable floor before winter arrives.
Invest if your model clears July at conservative covers on local-resident revenue alone.
Invest if your concept has genuine Fremantle independent identity — not replicable shopping-centre format.
Invest if you carry working capital for winter trough on South Terrace — summer banking discipline mandatory.
Walk away if you signed after one December Saturday without July modelling.
Walk away if you pay Cappuccino Strip rent for a format serving primarily local residents.
Walk away if heritage fit-out and compliance costs are not amortised into lease economics.
Which economy your block serves — South Terrace tourist-enhanced, CBD local, or South Fremantle residential.
July covers versus January on your specific frontage — decide if locals alone clear labour at quoted rent.
Nearest named competitors within 300m — Dolce Venezia, For The Record, Coccolicco, or The Old Synagogue.
Heritage overlay and fit-out compliance cost before LOI — add 8–15% to effective fit-out budget.
Noise and licensing history if late-trading format.
Working capital reserve sized for first winter trough, not first summer peak.
Tourist-enhanced peak, 50–60% winter compression. Best for formats with local winter floor and summer banking discipline.
Year-round local-resident rhythm. Best for neighbourhood café, considered dining, independent retail.
Stable local catchment, limited tourist flow. Best for neighbourhood formats and allied health.
Seasonal tourism-led dining. Best for seafood-led with roster discipline.
Operator Intelligence
Scored 1–10 from an operator perspective: higher always means better. Each dimension includes the reasoning behind the score.
Strong summer and weekend peaks on South Terrace — winter compression material on tourist-facing blocks.
Deep local loyalty when identity fits — tourist layer adds volatility more than stability.
Destination editorial retail works; South Terrace browse conversion is seasonal.
Creative-professional local base supports quality pricing when identity is earned.
Local-resident loyalty is durable once earned — prerequisite for winter survival on primary strips.
Dense incumbent field on South Terrace — differentiation and identity mandatory.
Cappuccino Strip rent often misaligned with winter local-only revenue — CBD and South Fremantle more sustainable for matched formats.
Fremantle station and port access strong; weekend parking competitive on South Terrace.
Significant October–April and Fringe World spikes — must be modelled as upside, not baseline.
Stable local base with moderate residential in-migration — tourist layer unchanged structurally.
When Fremantle trades
October–April tourist peak
Combined tourist and local peak on South Terrace — December Saturday is annual high-water mark.
Late January–February (Fringe World)
Concentrated arts-and-culture visitor injection — margin enhancer on South Terrace.
Weekday local (year-round)
CBD and South Fremantle carry stable resident rhythm — foundation for sustainable models.
June–August winter trough
Tourist flow drops 50–60% — South Terrace runs 35–40% of December Saturday volume; break-even test applies.
July (full month)
Stress-test month — model must survive on local-resident revenue at conservative covers.
Operator fit warning
Operators who signed after one summer Saturday without July modelling.
Local-resident formats paying Cappuccino Strip tourist-priced rent.
Generic or chain-adjacent concepts the Fremantle community rejects.
Operators without working capital for first winter trough on South Terrace.
Year-round local floor at rent sized for resident revenue — tourist upside optional.
Only viable when July clears labour on local regulars built during summer one.
Editorial product pulling deliberate visits beyond tourist browse.
Licence or variable structures matching tourism seasonality.
Appointment formats insulated from tourist volatility.
Late January–February spike as margin enhancer, not baseline.
South Terrace priced for peak combined demand — winter runs on locals at 35–40% of summer Saturday volume.
Generic formats fail to earn local loyalty — community rejects before winter exposes dependency on departed tourists.
Compliance and logistics add 8–15% effective fit-out — converts to rent-free burn if unbudgeted.
Operators who bank nothing from October–April reach first July without working capital for trough.
Common mistakes
Observing full tables in summer and signing fixed rent that does not adjust when tourist flow leaves by July.
Formats that read generic never build the winter floor — community preference forms in month one.
Compliance and logistics surprises convert to rent-free burn before first winter.
Underrated signals
Late January–February concentrates visitor spend — valuable upside when winter floor exists.
Fremantle-aligned concepts build referral-heavy resident base that carries every subsequent quiet period.
Suburb comparison
Subiaco trades lower tourism volatility and stronger weekday professional rhythm. Fremantle offers higher summer upside with mandatory winter discipline.
Victoria Park offers lower rent and thinner competition for developing concepts. Fremantle trades character premium and tourism layer for volatility.
Fremantle rewards operators who size rent to the economy they actually serve — local-resident floor on CBD and South Fremantle, explicit winter discipline on South Terrace.
Break even on locals alone before signing Cappuccino Strip rent. Tourist and Fringe World contribution is upside that requires working capital to harvest, not baseline revenue.
Related Perth reading
Fremantle suburb-level scoring averages tourist and local economies — it does not tell you whether your tenancy is South Terrace peak-rent or Market Street year-round local. Locatalyze runs address-level analysis surfacing seasonal flow patterns, competitor mapping, and winter-month revenue envelopes. For a precinct comparison of Fremantle against Subiaco, Leederville and eight other Perth café strips, read Why Perth café locations work: /blog/why-perth-cafe-locations-work-precinct-analysis.
Fremantle insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
Read Locatalyze’s data-led precinct article covering Fremantle alongside Subiaco, Leederville, Mount Lawley and more: https://www.locatalyze.com/blog/why-perth-cafe-locations-work-precinct-analysis — then run your specific address through an onboarding report.
Only when July covers clear labour on local-resident revenue built during summer one — tourist peak alone cannot justify fixed Cappuccino Strip rent.
Tourist flow drops 50–60% on primary strips June–August — models marginal on summer peak alone go cash-flow negative in July.
Local-resident base actively prefers independent identity — generic formats often fail to build the winter floor before first July.
Subiaco trades lower tourism volatility and stronger weekday professional base. Fremantle suits operators who accept seasonality with explicit winter planning.
Overlays and loading constraints commonly add 8–15% to effective fit-out cost — budget before lease signing, not after LOI.
Café 65, restaurant 67 and retail 68 sit within 3 points. The model is not choosing a format. The suburb verdict is VERIFY at 66/100.
No factor is in a tight band. Demand is 7/10, rent pressure 5/10, competition 5/10, and seasonality 4/10. The verdict comes from the weighted blend, not from one red flag.
Tourism dependency is 8/10. Restaurant and retail scores include that visitor component. The café score does not. Do not annualise a holiday week.
A competitor snapshot lists 30 venues. That is an observation from the snapshot, not evidence the suburb is under-supplied.
This is a reading of the five factors and three format scores on this page. It is not a rent quote, a competitor count, or a reason to sign a lease.
How to read these scores
Composite 66/100. The format scores sit within 3 points, so this panel does not pick a format.
Source
Locatalyze engine v7.4.0 plus cached local competitor evidence
Freshness
Competitor cache refreshed 27 June 2026
Confidence
Medium - 30 businesses sampled
Limitation
Fremantle scores screen the suburb, not the lease. The paid report tests frontage, rent, nearest competitors, and break-even at your exact address.
Evidence freshness
Scores
Engine v7.4.0; suburb-level model
Competition
Google Places cache refreshed 27 June 2026
Rent
No sourced asking-rent series — obtain current listings
Demographics
ABS Census 2021 is cited only where this page states a count. A score is not a census figure.
Factor Breakdown
Demand, rent, competition, seasonality, and tourism — scored and weighted for Australian commercial operators.
Business-Type Scores
Scores use engine-derived weights: cafés weight demand and rent most heavily; restaurants factor tourism; retail factors tourism and demand equally.
Analyst Notes — Fremantle
Demand 7/10: tourism uplift plus strong local demographic; heritage precinct drives weekend trade.
Seasonality 4/10: tourist-driven revenue creates significant winter-summer variance.
Methodology: Scores are engine-derived from five observable inputs (demand strength, rent pressure, competition density, seasonality risk, tourism dependency — each 1–10). These feed into business-type-specific weighted composites via a single scoring engine used across all markets. Scores are relative estimates calibrated across all Perth suburbs — a score of 80 indicates materially better conditions than 65; it is not a success probability or guarantee.
Run a free location check — named competitors, a rent benchmark, and location score, data confidence, and proceed / verify / avoid recommendation — for any Fremantle address.
Fremantle insights are suburb-level. Your free score checks a specific address — competitors, rent pressure, and a Proceed / Verify / Avoid recommendation.
Subiaco scores 75/100 on the same model.
Demand 8/10: Beaufort Street has the best entry timing in Perth — improving demographics, thin competition supply.
Demand 8/10: best rent-to-revenue ratio in inner Perth — 20% below Subiaco rents with comparable demographic quality.
Local competition
Ranked from cached Google Places data near the suburb centre. Validate at your lease address before signing.
Ranked by success score (rating, review depth, centrality) within ~1500m of the suburb centre.
What winners have in common
★★★★☆ 4.0 (698 reviews) · $$ · 861m from centre
If you are opening nearby: Target Fremantle is the benchmark retail here — $$ positioning is validated by review depth in this catchment — For new entrants: Niche or service-led retail beats another generalist shelf near Target Fremantle.
2. Fremantle Central Pharmacy (Compounding Chemist)
★★★★½ 4.9 (105 reviews) · 922m from centre
If you are opening nearby: 4.9★ with 105 reviews signals repeat custom, not novelty traffic — For new entrants: Niche or service-led retail beats another generalist shelf near Fremantle Central Pharmacy (Compounding Chemist).
3. Oz Australia
★★★★½ 4.7 (99 reviews) · 871m from centre
If you are opening nearby: 4.7★ with 99 reviews signals repeat custom, not novelty traffic — For new entrants: Niche or service-led retail beats another generalist shelf near Oz Australia.
4. Three Stories
★★★★½ 4.7 (72 reviews) · 919m from centre
If you are opening nearby: For new entrants: Niche or service-led retail beats another generalist shelf near Three Stories.
5. Kathmandu Fremantle
★★★★☆ 4.3 (85 reviews) · 852m from centre
If you are opening nearby: 4.3★ with 85 reviews signals repeat custom, not novelty traffic — For new entrants: Niche or service-led retail beats another generalist shelf near Kathmandu Fremantle.
Derived from venue counts and formats in our Google Places snapshot — not a guarantee of demand at your exact address.
Reason: Product-only retail is crowded online — hands-on services tied to a high-street address defend against e-commerce.
Ranked by success score (rating, review depth, centrality) within ~800m of the suburb centre.
What winners have in common
★★★★½ 4.9 (513 reviews) · 616m from centre
If you are opening nearby: Dolce Venezia is the benchmark café here — their 4.9★ and 513 reviews beat the 299-review peer average — For new entrants: Dolce Venezia is the benchmark café here — compete on speed, workspace utility, or an earlier breakfast daypart, not a bigger fit-out.
2. For The Record Coffee House
★★★★★ 5.0 (427 reviews) · 650m from centre
If you are opening nearby: For The Record Coffee House (Dominant) shows what execution looks like at this score tier — their 5.0★ and 427 reviews beat the 308-review peer average — For new entrants: Near For The Record Coffee House, differentiate through pastry-led counter — generic third-wave coffee will not stand out.
★★★★☆ 4.4 (731 reviews) · $$ · 575m from centre
If you are opening nearby: their 4.4★ and 731 reviews beat the 274-review peer average — $$ positioning is validated by review depth in this catchment — For new entrants: The Old Synagogue's volume comes from breadth — narrow to one daypart (early breakfast or late specialty coffee) rather than their full menu.
4. Coccolicco
★★★★★ 5.0 (278 reviews) · 617m from centre
If you are opening nearby: Coccolicco (Dominant) shows what execution looks like at this score tier — 5.0★ with 278 reviews signals repeat custom, not novelty traffic — For new entrants: Coccolicco is beatable on single-origin filter led — avoid matching incumbents' full menu breadth.
5. Cafe on Hampton
★★★★½ 4.9 (272 reviews) · 594m from centre
If you are opening nearby: Cafe on Hampton (Dominant) shows what execution looks like at this score tier — 4.9★ with 272 reviews signals repeat custom, not novelty traffic — For new entrants: Cafe on Hampton is beatable on pastry-forward with a limited hot menu — avoid matching incumbents' full menu breadth.
Ranked by success score (rating, review depth, centrality) within ~1000m of the suburb centre.
What winners have in common
★★★★☆ 4.4 (3,569 reviews) · $$ · 675m from centre
If you are opening nearby: Sail and Anchor is the benchmark restaurant here — their 4.4★ and 3,569 reviews beat the 1,389-review peer average — $$ positioning is validated by review depth in this catchment.
★★★★☆ 4.3 (2,459 reviews) · $$$ · 999m from centre
If you are opening nearby: their 4.3★ and 2,459 reviews beat the 1,512-review peer average — $$$ positioning is validated by review depth in this catchment — For new entrants: Focus on a specific occasion (date night, quick lunch, or group dining) that Bread in Common does not dominate.
★★★★☆ 4.3 (2,182 reviews) · $$ · 973m from centre
If you are opening nearby: their 4.3★ and 2,182 reviews beat the 1,543-review peer average — $$ positioning is validated by review depth in this catchment — For new entrants: Focus on a specific occasion (date night, quick lunch, or group dining) that Clancy's Fish Pub does not dominate.
4. Nunzio's Restaurant
★★★★½ 4.7 (855 reviews) · $$ · 759m from centre
If you are opening nearby: Nunzio's Restaurant (Dominant) shows what execution looks like at this score tier — 4.7★ with 855 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment.
5. Benny's Bar & Cafe
★★★★☆ 4.3 (1,426 reviews) · $$ · 826m from centre
If you are opening nearby: 4.3★ with 1,426 reviews signals repeat custom, not novelty traffic — $$ positioning is validated by review depth in this catchment — For new entrants: Benny's Bar & Cafe already pulls the wine-and-snacks crowd — pick a different occasion (family early dining, counter lunch, or late casual) instead of another small-plates room.
Derived from venue counts and formats in our Google Places snapshot — not a guarantee of demand at your exact address.
Reason: Tourism dependency is elevated — visitors want authentic local food without fine-dining price tags.